
Building a Retirement Plan After 45: A Step-by-Step Approach
A practical, structured process for adults in their mid-40s and beyond to assess where they stand, set targets, and take consistent action toward retirement.
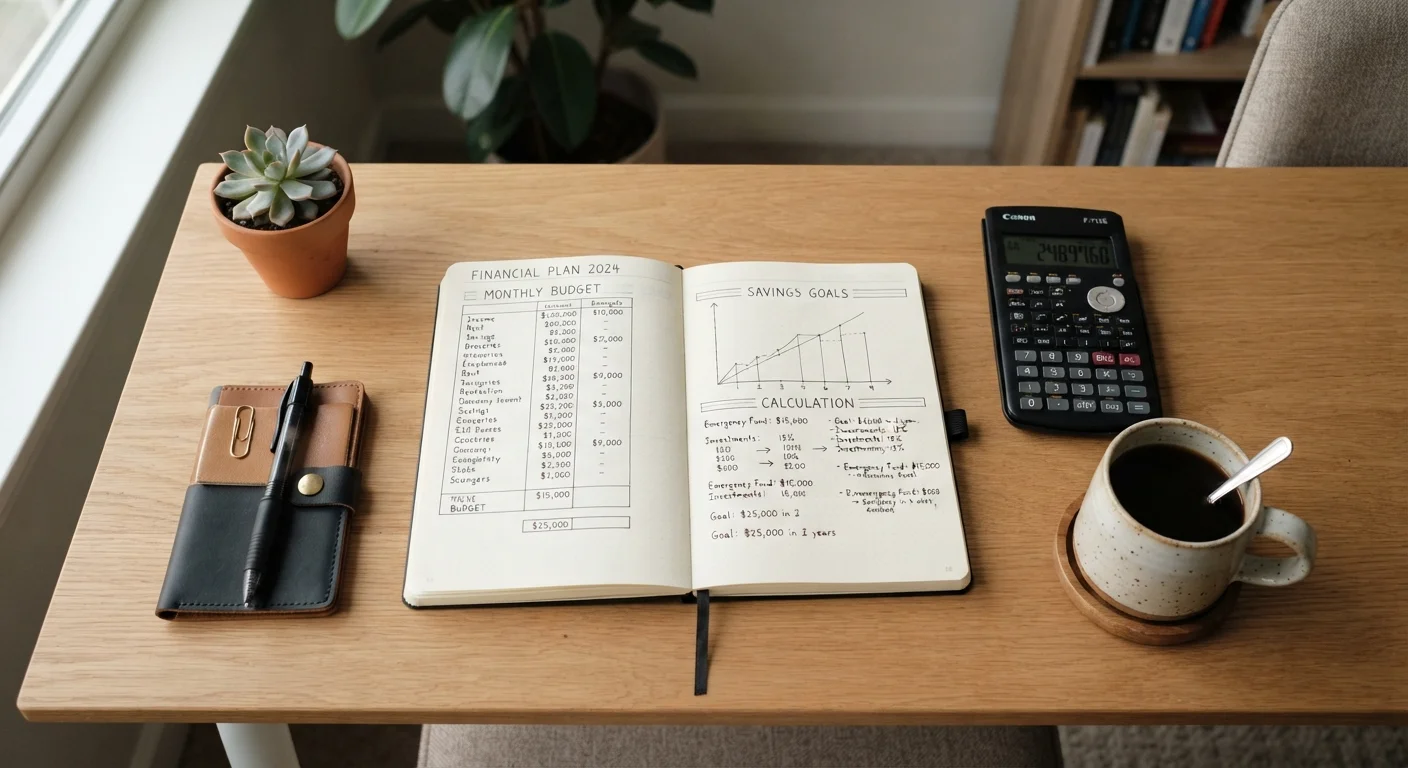
Photo: shapingfinances.com editorial
—— In This Article
Key Takeaways
- Starting a retirement plan at 45 or later still allows meaningful accumulation through catch-up contributions and compounding.
- IRS catch-up contribution rules let adults 50 and older add extra funds to 401(k) and IRA accounts each year.
- A clear net-worth snapshot and projected income gap are the foundation of every catch-up strategy.
- Reducing high-interest debt alongside saving improves your net retirement position more than saving alone.
- Social Security claiming age significantly affects lifetime benefit totals and should be modeled before retiring.
- A fee-only, fiduciary financial adviser can translate general principles into a plan for your specific situation.
Why starting at 45 is workable, not ideal
Adults who reach their mid-40s without a formal retirement plan often carry a mix of regret and uncertainty. That reaction is understandable, but it can obscure a practical reality: a 45-year-old with an average life expectancy still has roughly 20 years of potential savings ahead, and a 55-year-old has about 10. Those time windows are shorter than a 25-year-old's, but they are long enough to build a meaningful base if the effort is consistent and structured.
The steps below form a repeatable process. Work through them in order the first time, then revisit each section annually as your circumstances change. This article provides general financial education, not personalized advice. Consult a qualified financial professional before acting on anything here.
What you need before you start
Gathering a few documents before working through the steps will prevent delays.
What you will need
Step-by-step retirement planning process
Follow these steps in sequence. Each one builds on the one before it.
Calculate your current net worth
List every asset you own: retirement accounts, taxable brokerage accounts, real estate equity, savings, and any cash-value life insurance. Then list every liability: mortgage balance, car loans, student loans, credit card balances. Subtract total liabilities from total assets. The result is your net worth today, which is the baseline every future decision references.
Be precise. Rounding a 401(k) balance to the nearest thousand is fine; omitting an account because you forgot its password is not. Gather actual statements.
Estimate your retirement income gap
Determine how much annual income you will need in retirement. A common starting figure is 70% to 80% of your current pre-tax income, though your specific spending plan may differ. Next, estimate the income you expect to receive automatically: Social Security benefits (from your SSA statement) and any pension payments. Subtract that guaranteed income from your target annual income. The remainder is your income gap, the amount your savings must fund each year.
To estimate how large a portfolio is needed to cover that gap, multiply the annual gap by 25. This figure comes from the widely cited 4% withdrawal rate guideline, which holds that withdrawing 4% of a portfolio annually has historically supported a 30-year retirement. Note that past performance does not guarantee future results, and your actual withdrawal rate should be reviewed with an adviser.
Maximize tax-advantaged contributions
For the 2024 tax year, the 401(k) contribution limit is $23,000. Adults aged 50 and older may add a catch-up contribution of $7,500, bringing the total to $30,500. For traditional and Roth IRAs, the 2024 limit is $7,000, with a $1,000 catch-up for those 50 and older, for a total of $8,000. (These figures are set by the IRS and adjusted periodically for inflation. Verify current limits at irs.gov before contributing.)
If your employer matches 401(k) contributions, contribute at least enough to capture the full match before directing money elsewhere. An unmatched employer contribution is forgone compensation. After capturing the match, consider maxing out a Roth IRA if your income is within IRS phase-out limits, then return to the 401(k) for additional contributions.
For broader saving habits that complement these contributions, see practical saving strategies that accelerate retirement fund growth.
Review your investment allocation
A portfolio appropriate for a 30-year-old is often too aggressive for someone 15 years from retirement, and one appropriate for a retiree is often too conservative for someone still accumulating. A common framework is to subtract your age from 110 to get a rough equity percentage (for example, 65% stocks at age 45), though your actual risk tolerance and timeline may support a different mix.
Within equities, broad diversification across domestic and international markets, and across market capitalizations, reduces the impact of any single market segment declining sharply. Within fixed income, bond duration (how sensitive a bond's price is to interest rate changes) matters more as retirement approaches.
Review your allocation annually and after any major life event. Rebalancing means selling assets that have grown beyond their target weight and buying those that have fallen below it, which enforces a buy-low, sell-high discipline without requiring market predictions.
Model your Social Security and income layering strategy
Social Security is one of the few inflation-adjusted lifetime income sources available to most Americans. Delaying your claim past full retirement age increases your monthly benefit by 8% for each year you wait, up to age 70. A worker with a full retirement age benefit of $2,000 at 67 would receive approximately $2,480 at 70.
Whether delaying makes sense depends on your health, other income sources, and whether you are married (spousal and survivor benefits add complexity). The goal is to layer income sources so that fixed expenses are covered by predictable, guaranteed income (Social Security, any pension) and discretionary spending draws from your portfolio. For a detailed look at layering multiple income streams, see coordinating Social Security, pensions, and investment income.
Build a written retirement income plan
At this stage you have a net worth figure, an income gap estimate, maximized contribution targets, an allocation framework, and a Social Security claiming strategy. Combine these into a single written document: your target retirement date, your projected portfolio balance at that date (using a conservative assumed return, typically 5% to 6% nominal), your expected income sources, and your annual withdrawal plan.
Review this document with a fee-only, fiduciary financial adviser, one who is legally required to act in your interest and who charges a flat fee or hourly rate rather than commissions. For income options beyond withdrawals, passive income streams that can last through retirement outlines dividends, rental income, and annuities as supplemental sources. A broader look at income planning is available through the retirement income hub.
Common obstacles and how to address them
Debt competing with savings
High-interest consumer debt reduces the effective return on every dollar you save. Paying off a credit card balance at 22% annual interest is mathematically equivalent to earning a 22% guaranteed return, which no investment reliably provides. For a structured approach to managing both simultaneously, see building a debt payoff plan when retirement is 10 to 20 years away.
High fixed expenses
Housing, transportation, and subscriptions that made sense at 35 may consume more of your income than your retirement timeline can absorb. Moderate lifestyle adjustments made now can redirect hundreds of dollars monthly toward savings without requiring dramatic changes. Downsizing and lifestyle adjustments that can fund retirement covers this in practical terms.
Insurance gaps
Long-term care costs and gaps in health coverage are among the largest unplanned expenses retirees face. If you are in your 50s, now is a logical time to audit your existing policies. A step-by-step coverage review for people in their 50s walks through that process.
This article is for informational and educational purposes only. It is not personalized financial, investment, tax, or legal advice. Figures cited reflect IRS rules as published; contribution limits and tax laws are subject to change. Consult a licensed financial adviser, tax professional, or attorney for guidance specific to your situation.
Retirement Planning Editorial Team
Retirement Planning Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View author profile