
Saving in a High-Cost Household: Tactics That Work When Expenses Feel Immovable
Practical strategies for adults 40-60 who feel squeezed by mortgage, family, and lifestyle costs but still want to build a meaningful retirement cushion.
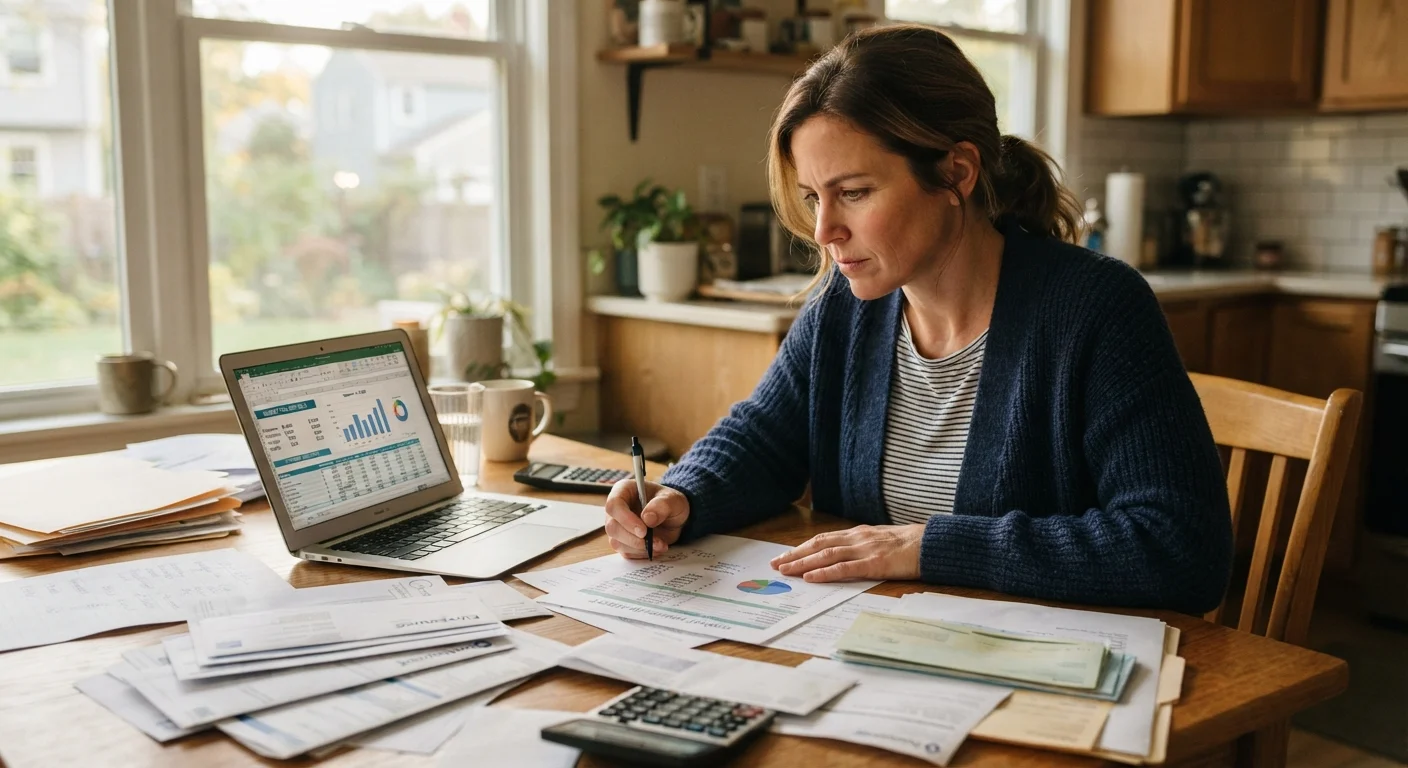
Photo: shapingfinances.com editorial
—— In This Article
Key Takeaways
- Automating contributions removes the temptation to spend money before it is saved.
- Catch-up contributions after age 50 can significantly increase annual retirement savings limits.
- Auditing recurring subscriptions and insurance premiums often uncovers hundreds of dollars annually.
- Directing windfalls and raises to retirement accounts before adjusting lifestyle preserves momentum.
- Carrying high-interest debt while under-saving is a double drain that compounds over time.
Why high-cost households face a specific savings problem
Households in the 40-60 age bracket often carry a dense stack of fixed or near-fixed obligations: a mortgage in its middle years, college tuition, aging-parent support, and lifestyle costs that rose gradually alongside income. Each individual expense feels justified. Together, they can make the idea of saving more feel arithmetically impossible.
The problem is not usually that there is nothing to save. It is that every dollar is already assigned before it arrives. Without a deliberate system, retirement contributions lose the competition for cash flow every month. The tactics below address that structural issue rather than asking you to simply spend less on things you value.
For a broader look at where your saving habits currently stand, the Mid-Life Money Audit checklist offers a structured starting point.
Tactics that move the needle when expenses feel immovable
These practices are ordered roughly by the effort required to implement them, starting with the ones most people can act on this week.
Automate retirement contributions at the source before discretionary spending begins.
When contributions leave your paycheck or bank account before you see the balance, you adapt spending to what remains rather than deciding each month whether to save. This approach, sometimes called paying yourself first, is one of the most consistent predictors of whether people actually build retirement savings over time.
Use catch-up contribution limits fully once you turn 50.
The IRS allows workers aged 50 and older to contribute more to 401(k) plans and IRAs than younger savers can. These higher limits exist specifically because mid-life savers often have more earning capacity but less time for compound growth. Leaving that extra room unused is a missed opportunity that cannot be recovered later.
Run an annual audit of recurring expenses, especially subscriptions and insurance premiums.
Recurring costs are the category most likely to grow unnoticed. Subscriptions stack up, insurance premiums drift upward at renewal, and membership fees persist after the service becomes marginal. An annual line-by-line review forces each recurring cost to justify itself against your current priorities.
Redirect windfalls and raises to retirement accounts before adjusting your spending baseline.
Lifestyle costs tend to rise in proportion to income unless a deliberate rule governs new money. Committing a portion of each income increase to savings before it enters your regular budget prevents the incremental expansion of fixed costs that makes high-cost households feel permanently squeezed.
Address high-interest debt as a savings priority, not a separate financial problem.
Carrying a balance at 18-25 percent interest while earning 4-6 percent on savings is a net loss every month. Paying down high-interest debt is a guaranteed return at the rate of that interest, with no market risk attached. The two goals compete for the same dollars and should be planned together. See also: why minimum payments can extend debt for decades.
If debt payments are consuming a large share of your monthly cash flow, a structured debt payoff plan can help you free up room for retirement contributions without abandoning progress on balances.
Making the most of what you already earn
Income increases in your 40s and 50s are an opportunity that closes gradually. When a raise or bonus arrives, directing even half of the after-tax gain to a retirement account before adjusting your spending baseline locks in progress. The same logic applies to tax refunds, inheritances, or proceeds from selling assets. These events are unpredictable, but having a standing rule about where windfalls go removes the decision in the moment.
Lifestyle adjustments do not have to be dramatic to matter. Moderate changes in your 40s and 50s can redirect meaningful sums toward retirement without sacrificing quality of life. The automation strategies outlined here make those redirections stick by removing reliance on monthly willpower.
High-cost households also benefit from auditing their debt picture periodically. Managing debt methodically in the years before retirement protects the contributions you are already making and reduces financial stress as your target date approaches.
This article is for general informational purposes only and does not constitute personalized financial, tax, or investment advice. Contribution limits, tax treatment, and eligibility rules change over time and vary by individual circumstances. Consult a qualified financial adviser or tax professional before making decisions about your retirement savings strategy.
Saving Strategies Editorial Team
Saving Strategies Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View author profile