
Should You Pay Down Debt or Invest for Retirement First?
One of the trickiest financial questions for adults in their 40s and 50s. Explore the key factors that help you think through this common dilemma clearly.
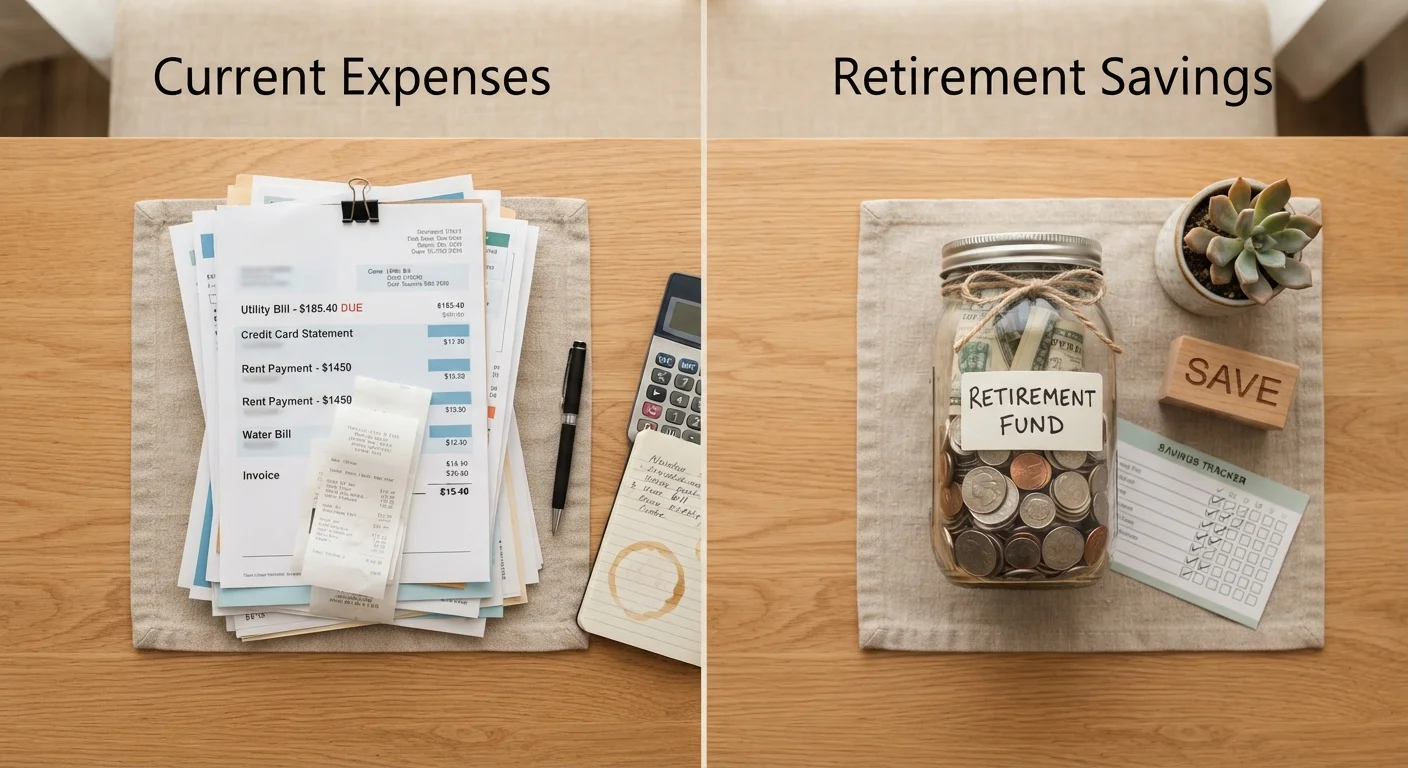
Photo: shapingfinances.com editorial
—— In This Article
Key Takeaways
- High-interest debt (above roughly 7%) typically costs more than diversified investments can reliably return, making paydown the priority.
- Employer 401(k) matching contributions are effectively a 50% to 100% instant return, and skipping them to pay debt is rarely worth it.
- Low-interest debt such as a mortgage below 4% may be worth carrying while investing, because the math often favors investing.
- Carrying significant debt into retirement shrinks the income available from fixed sources like Social Security and withdrawals.
- Most adults in their 40s and 50s benefit from doing both simultaneously at proportions determined by their specific interest rates and timelines.
Why this question does not have a one-size answer
Adults in their 40s and 50s face a genuine mathematical tension. Every dollar directed at debt reduces guaranteed interest costs. Every dollar invested has the potential to compound, but with no certainty of return. The decision hinges on a comparison between those two numbers: the interest rate you are paying versus the after-tax return you could reasonably expect from investing.
Debt with an interest rate above roughly 7% is expensive enough that paying it down often beats investing in a diversified portfolio, where long-run average returns are not guaranteed and can vary significantly across decades. Debt below 4% or 5% is cheap enough that investing additional dollars is frequently the stronger financial move over a long horizon. The middle range, roughly 5% to 7%, is genuinely ambiguous and depends on your tax situation, risk tolerance, and how close you are to retirement.
The Federal Reserve's Survey of Consumer Finances has consistently found that households in their 40s and 50s carry debt across multiple categories simultaneously, including mortgages, auto loans, and revolving credit. That mix matters because the right answer for a 6.5% car loan is different from the right answer for a 3.2% mortgage.
For a fuller look at the real cost of carrying balances past your working years, see what debt in retirement actually costs.
The employer match: a decision that comes before everything else
If your employer matches 401(k) contributions, capturing that match is almost always the first priority, before paying extra on any debt. A 50% match on contributions up to 6% of salary is the equivalent of a guaranteed 50% return on those dollars, an outcome no debt paydown strategy can match.
Skipping the match to accelerate debt repayment is one of the more common and costly mistakes the debt myths that keep people stuck in their 40s and 50s article covers in detail. The practical rule is straightforward: contribute enough to capture the full employer match, then redirect remaining cash flow based on your debt interest rates.
Capture the full employer match first
Before directing extra cash at debt, confirm you are contributing at least enough to your 401(k) to receive your employer's full match. Skipping even a partial match forfeits dollars that cannot be recovered later. Once the match is secured, then apply the interest-rate comparison to decide where additional funds go.
How interest rate determines the right balance
Once you have secured any employer match, the comparison becomes interest rate versus expected investment return.
| Debt type | Typical rate range | Suggested approach | |
|---|---|---|---|
| Credit card debt | Credit card debt | 15% to 25%+ | Pay down aggressively before increasing investments |
| Personal loan | Personal loan | 8% to 15% | Prioritize paydown alongside minimum retirement contributions |
| Auto loan | Auto loan | 5% to 8% | Balance paydown with investing; borderline case |
| Student loan (federal) | Student loan (federal) | 4% to 7% | Evaluate income-driven repayment options; invest alongside |
| Mortgage | Mortgage | 3% to 5% | Often favors investing; verify after-tax rate first |
A mortgage at 3.5% acquired several years ago is a case where the math generally favors investing, because the after-tax cost of that debt is lower than what a diversified long-term portfolio has historically returned, though past returns do not guarantee future ones. A credit card at 22% APR is a case where no reasonable investment strategy reliably outpaces that guaranteed cost.
Your tax situation adds a layer of nuance. Mortgage interest may be deductible for some filers, reducing the effective rate further. Contributions to a traditional 401(k) or IRA reduce taxable income now, which improves the after-tax math of investing. A licensed tax professional can clarify how these factors apply to your specific circumstances.
For a side-by-side look at retirement account options available to late savers, Traditional IRA vs. Roth IRA for adults in their 40s and 50s covers the key trade-offs.
Time horizon changes the calculation
A 45-year-old with 20 years until retirement has time for compounding to work, which tilts the math toward investing even while carrying moderate-rate debt. A 58-year-old planning to retire in seven years faces a different reality: less time for markets to recover from a downturn, and a higher risk that debt obligations will consume a meaningful share of retirement income.
The CFPB has noted that carrying debt into retirement on a fixed income can create cash-flow problems that erode financial security faster than pre-retirement calculations suggest. Reducing fixed monthly obligations before income drops is a form of risk management, separate from the pure interest-rate comparison.
If you are building a concrete plan around this timeline, a debt payoff plan for those with 10 to 20 years until retirement offers a step-by-step framework.
Readers who want to understand how their savings rate and investment return interact at this life stage can also explore savings rate vs. investment return in your 40s and 50s.
This article provides general financial information for educational purposes only and is not personalized financial, tax, or investment advice. Your situation depends on factors specific to you. Consult a qualified financial adviser, tax professional, or attorney before making decisions about debt repayment or retirement investing.
Debt Management Editorial Team
Debt Management Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View author profile