
Common Investing Errors That Erode Retirement Savings
Even well-intentioned investors make costly mistakes. This article examines the most frequent missteps adults make in the years before retirement and how to sidestep them.
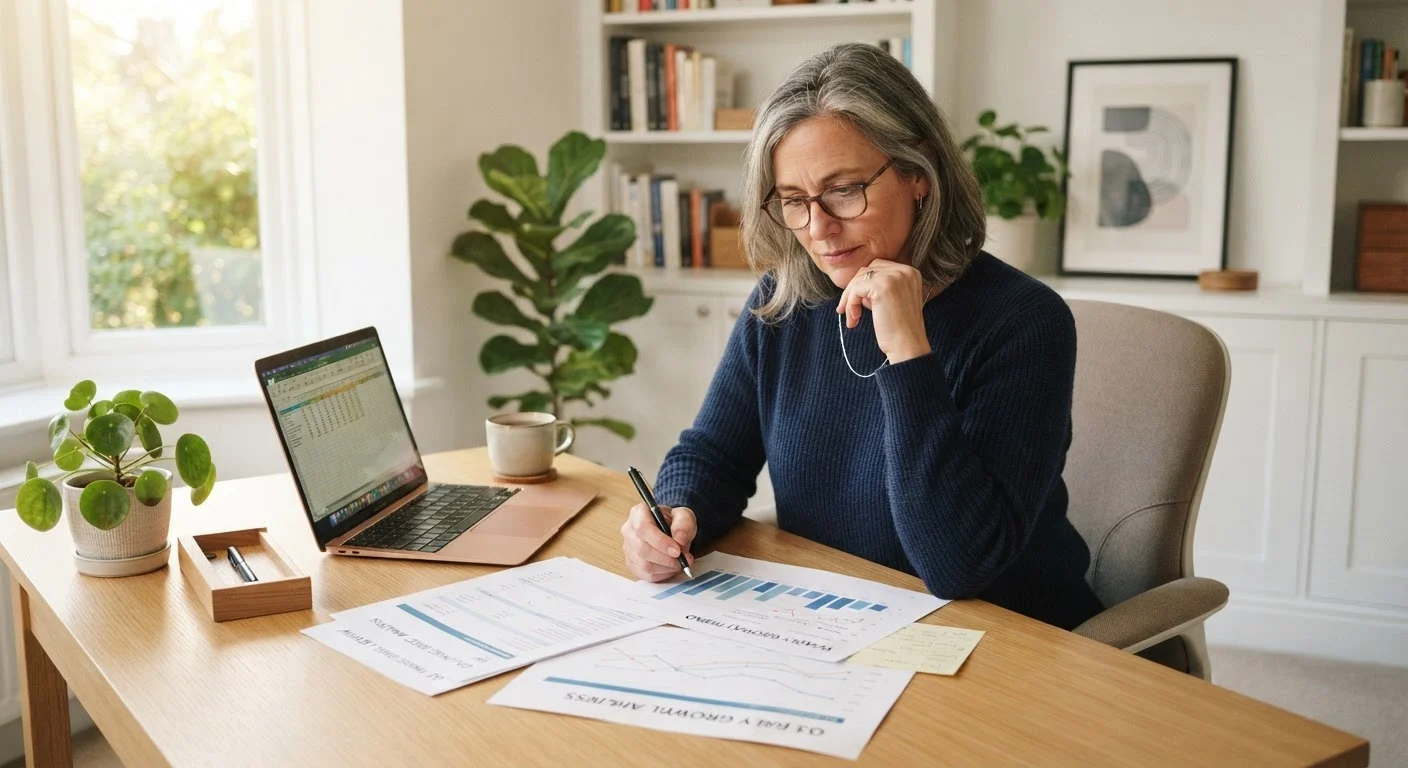
Photo: shapingfinances.com editorial
—— In This Article
Key Takeaways
- Waiting too long to start or rebalance a portfolio costs more than most investors expect.
- Emotional reactions to market swings are among the most damaging behaviors for long-term returns.
- Ignoring fees and tax drag can quietly reduce a portfolio's value over decades.
- Concentrating savings in too few assets or a single employer's stock adds unnecessary risk.
- A qualified financial adviser can help you identify blind spots before they become permanent losses.
Why small missteps cost more than investors expect
Retirement savings errors rarely look catastrophic in the moment. A year of skipped contributions, an unbalanced portfolio, or a panicked sell-off during a downturn can each seem manageable. Over time, these decisions compound alongside your money, and not in the direction you want.
Adults in their 40s and 50s face a specific challenge: there is enough runway left to correct course, but not so much that errors can simply be outwaited. Catching up on retirement savings becomes significantly harder once compounding has been interrupted, which is why identifying these patterns early matters.
The mistakes below are not signs of carelessness. Most happen to attentive, well-intentioned people because investing involves real uncertainty and the feedback loops are slow. Understanding why each error occurs is the first step toward changing the behavior.
Delaying investment contributions until conditions feel 'right'.
Why it happens: Uncertainty about the economy, political news, or personal finances leads many people to wait for a clearer signal. That signal rarely comes.
Reacting emotionally to short-term market volatility.
Why it happens: Watching account balances drop triggers a fear response that can feel like a rational warning to act. For long-term investors, it usually is not.
Underestimating the drag of investment fees on long-term growth.
Why it happens: A fee expressed as a small percentage, such as 1% annually, does not feel significant. Compounded over 20 years on a growing balance, it can reduce a portfolio's final value by tens of thousands of dollars.
Holding a portfolio that was never rebalanced after being set up.
Why it happens: Once accounts are opened, many investors assume the allocation will stay correct on its own. Asset values shift at different rates, so a portfolio drifts from its original mix without any action.
Concentrating retirement savings in a single stock or a narrow group of assets.
Why it happens: Employer stock is often offered at a discount or builds familiarity over years of watching it rise. A few winning picks can create overconfidence in concentration as a strategy.
Ignoring the tax treatment of different account types.
Why it happens: Tax rules for retirement accounts are complicated, and many investors place assets in accounts without considering which combination would be most tax-efficient over time.
How fees and taxes quietly reduce what you keep
Investment returns get most of the attention, but what an investor actually accumulates depends on what survives fees and taxes. A fund earning 7% annually before a 1% expense ratio delivers 6% to the investor. That gap widens as the portfolio grows.
1%
Annual fee that can erase years of gains
A 1% annual fee difference on a $250,000 portfolio can result in a six-figure reduction in final balance over a 20-year period, based on standard compound-growth modeling.
10+ years
Typical cost of delaying retirement contributions
An investor who begins contributing at 50 instead of 40 must save roughly twice as much per month to reach the same retirement balance, due to the reduced compounding window.
Tax treatment is equally consequential. Money in a tax-deferred account such as a traditional 401(k) grows without annual tax drag but is taxed as ordinary income at withdrawal. A Roth account taxes contributions upfront and allows qualified withdrawals tax-free. Placing the right assets in each account type is a legitimate planning consideration, and one worth reviewing with a tax professional. For a deeper look at how withdrawal strategy interacts with these decisions, see the four percent rule and other withdrawal strategies.
Fees and tax drag are two areas where investors have direct control. Reviewing both at least once a year is a concrete and actionable habit. For comparison, saving pitfalls that quietly erode retirement progress in mid-life covers the behavioral side of the same problem.
Selling during a market downturn locks in losses
When markets fall sharply, the impulse to move savings to cash feels protective. In practice, selling after a decline converts a paper loss into a real one and leaves investors out of position when prices recover. Historically, many of the strongest single-day market recoveries follow closely after the worst declines, meaning investors who exit often miss the rebound.
Building habits that protect a portfolio over time
Avoiding these errors does not require extraordinary discipline. It requires a small number of deliberate processes: automatic contributions, annual rebalancing, periodic fee reviews, and a written investment plan you return to when markets become difficult.
If you have been told that investing is too complex or too risky to start late, that belief itself may be the first obstacle. Investing myths that keep late starters on the sidelines addresses several of those assumptions directly.
Addressing insurance gaps matters too. Unexpected medical or long-term care costs can unwind years of careful saving faster than any market correction. Insurance gaps that can quietly drain a retirement nest egg covers where those risks tend to appear.
The investors who reach retirement in the best position are rarely those who found the perfect strategy. They are the ones who avoided the most damaging errors for the longest period of time.
This article is for general informational and educational purposes only. It does not constitute personalised financial, investment, tax, or legal advice. Consult a licensed financial adviser or tax professional before making decisions about your retirement savings.
Investing Essentials Editorial Team
Investing Essentials Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View author profile