
The Four Percent Rule and Other Withdrawal Strategies
What is the four percent rule, where did it come from, and is it still a reliable guide for how much you can safely withdraw from savings each year?
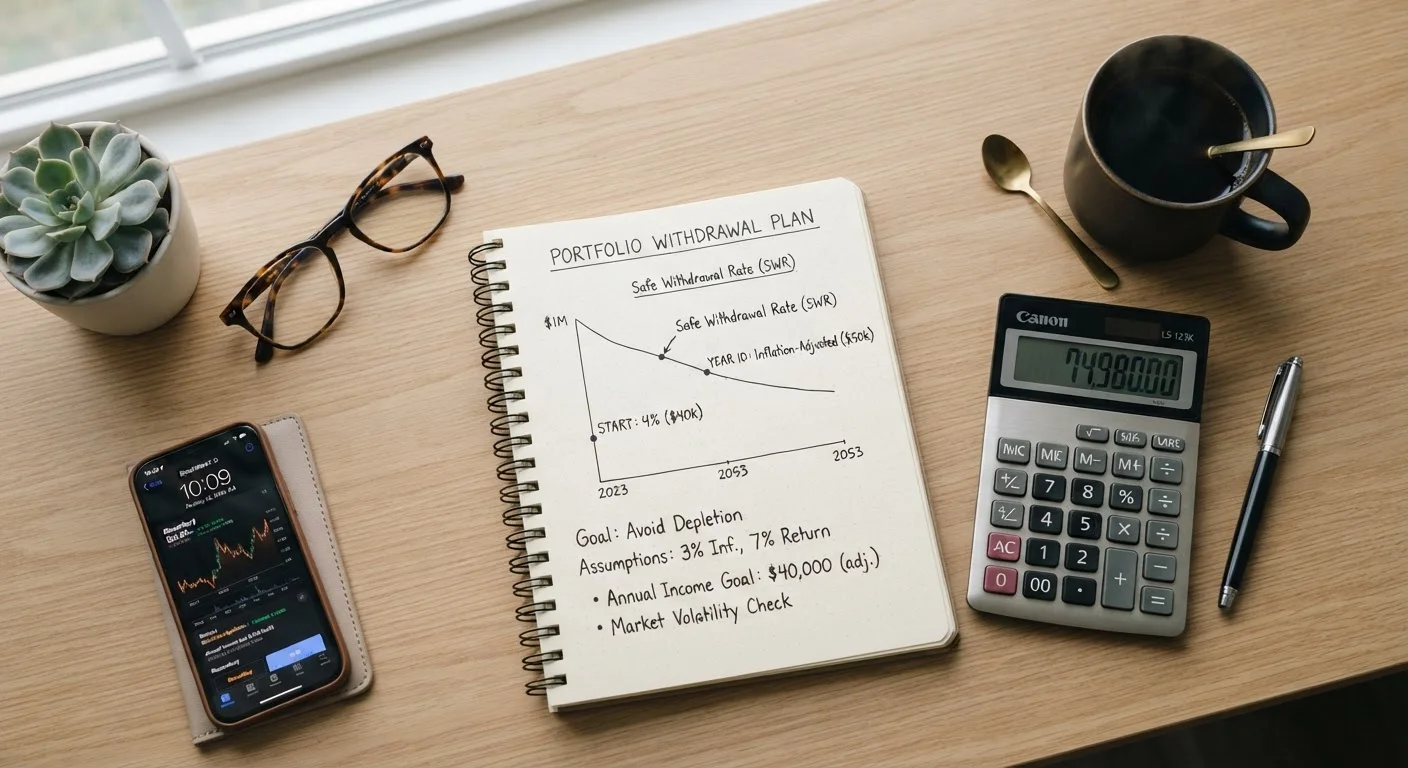
Photo: shapingfinances.com editorial
—— In This Article
Key Takeaways
- The four percent rule was designed for a 30-year retirement with a diversified stock-and-bond portfolio.
- It is a planning guideline, not a guaranteed safe withdrawal rate for every retiree.
- Longer retirements, higher expenses, or lower expected returns may require a more conservative rate.
- Other strategies such as dynamic spending and bucket approaches can reduce sequence-of-returns risk.
- Social Security and pension income can reduce the amount you need to withdraw from savings each year.
- A licensed financial adviser can help you choose a withdrawal strategy suited to your situation.
Where the four percent rule came from
In 1994, financial planner William Bengen published research testing how long portfolios held by retirees would last under various withdrawal rates. He used actual U.S. stock and bond return data from 1926 onward and found that a portfolio split roughly 50/50 between stocks and bonds could sustain a 4% initial withdrawal, adjusted each year for inflation, through every 30-year retirement period in his dataset.
Researchers at Trinity University later produced widely cited follow-up work reaching broadly similar conclusions. That body of research gave the 4% figure its staying power in retirement planning conversations.
The rule was always described as a guideline for a specific scenario: a 30-year retirement, a balanced portfolio, and U.S. market conditions as they existed over most of the 20th century. Bengen himself has since noted that the rate could be pushed modestly higher in favorable conditions, and lower in less favorable ones. For a deeper look at how to estimate your total savings target alongside this guideline, see how much money you actually need to retire.
Why the rule has limits in practice
Several realities complicate a straightforward application of the four percent rule today.
Longer retirements. Retiring at 60 rather than 65 may mean a 35-year or 40-year horizon. The original research targeted 30 years, and survival rates fall as the time period extends.
Lower expected returns. Bond yields have been lower in recent decades than they were during much of the period Bengen studied. Some financial researchers argue that a 3% to 3.5% initial rate is more appropriate given current market expectations, though projections involve genuine uncertainty.
Spending patterns change. Many retirees spend more in early retirement when they are active, less in mid-retirement, and more again in later years when healthcare costs rise. A fixed inflation-adjusted withdrawal ignores that variability.
Taxes matter. The rule does not account for the tax treatment of withdrawals. Money pulled from a traditional IRA or 401(k) counts as ordinary income, which affects your net spending power and could influence decisions about Roth conversions or account sequencing. Reviewing common investing errors that erode retirement savings can help you avoid compounding these issues.
Match your withdrawal rate to your income sources
Before settling on a withdrawal percentage, add up guaranteed income from Social Security, pensions, or annuities. Subtract that from your expected annual expenses. Your portfolio only needs to fill the gap, which may put your effective withdrawal rate well below 4% even on a modest portfolio.
Other withdrawal strategies worth knowing
Because the four percent rule is rigid, many planners use it alongside or in place of more flexible approaches.
Dynamic spending
Dynamic spending adjusts your withdrawal amount each year based on portfolio performance. In years when the market rises, you may withdraw a bit more. When it falls, you pull back. This approach reduces the risk of running out of money but requires some flexibility in your spending.
Guardrail strategies
Guardrail strategies set upper and lower spending thresholds. If your withdrawal rate rises above a set ceiling because the portfolio has fallen, you cut spending. If it falls below a floor because the portfolio has grown, you can spend more. The Guyton-Klinger framework is one well-documented example of this approach.
The bucket strategy
A bucket strategy separates your savings into short-term (cash), medium-term (bonds), and long-term (equities) pools. You spend from the short-term bucket first, refilling it periodically from the others. This can make it easier to avoid selling equities during a downturn, which is the core risk the four percent rule tries to address through its conservative rate. See our step-by-step drawdown framework for practical guidance on sequencing withdrawals.
77%
Increase in Social Security benefit from delaying to age 70
Delaying Social Security from age 62 to age 70 can increase the monthly benefit by approximately 77%, according to Social Security Administration data.
30 years
Retirement horizon the four percent rule targets
William Bengen's original 1994 research tested withdrawal rates against 30-year retirement periods using historical U.S. market data from 1926 onward.
3-3.5%
Conservative withdrawal rate suggested by some researchers
Some financial researchers recommend a lower initial rate for retirees facing longer horizons or lower expected returns than those in Bengen's historical dataset.
How Social Security and pensions fit in
The four percent rule addresses only portfolio withdrawals. Guaranteed income sources change the picture significantly.
Social Security benefits, once claimed, last for life and include annual cost-of-living adjustments. Delaying your claim from age 62 to age 70 increases your monthly benefit by roughly 77%, according to Social Security Administration data. A higher guaranteed monthly income means less pressure on your portfolio and a lower effective withdrawal rate needed to cover expenses.
Pensions function similarly. If a pension covers a large share of fixed expenses, your portfolio can afford to be more growth-oriented and may not need to generate as much income directly.
When guaranteed income covers core costs, some retirees use their portfolio exclusively for discretionary spending. That approach can tolerate more variable withdrawal amounts and may allow the portfolio to last longer. Your saving strategy in the years before retirement affects how large a portfolio you bring into that equation.
This article is for general informational purposes only and does not constitute personalized financial, tax, or investment advice. Consult a licensed financial adviser before making decisions about your retirement income strategy.
Frequently Asked Questions
Retirement Income Editorial Team
Retirement Income Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View author profile