
Rebalancing a Portfolio: When to Do It and Why It Matters
Over time, market movements drift your portfolio away from its intended mix. Discover how rebalancing works, when to trigger it, and what approach suits most investors.
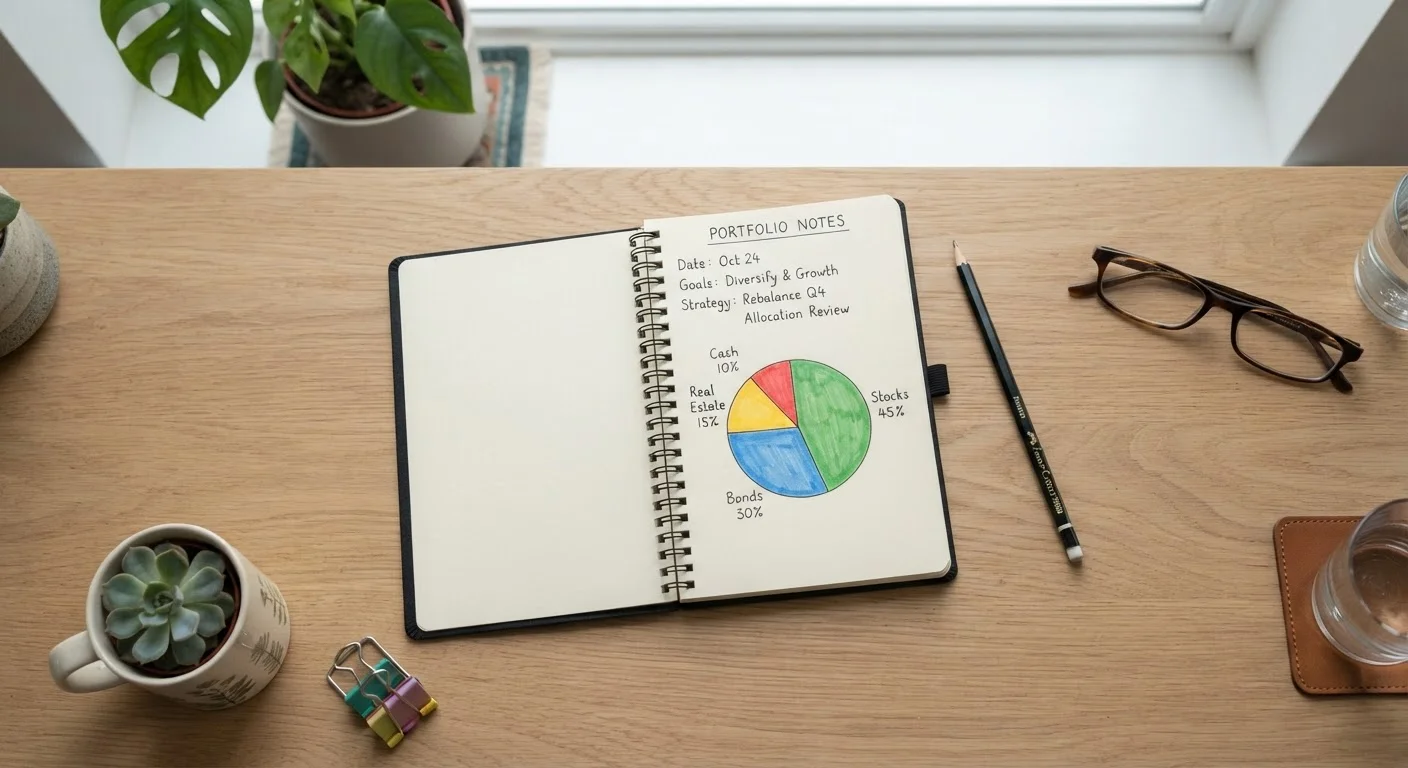
Photo: shapingfinances.com editorial
—— In This Article
Key Takeaways
- Market movements gradually shift your portfolio away from the asset mix you originally chose.
- Rebalancing restores your intended balance between stocks, bonds, and other asset classes.
- Two practical triggers are calendar-based rebalancing and threshold-based rebalancing.
- Tax implications and transaction costs should factor into every rebalancing decision.
- Rebalancing does not guarantee gains or prevent losses, but it does manage risk over time.
Why your portfolio drifts over time
When you first set up a portfolio, you choose a specific mix of assets: perhaps 60% in stocks and 40% in bonds. That split reflects your risk tolerance, your time horizon, and how close you are to retirement. The problem is that markets do not hold still.
If stocks have a strong year, your stock allocation may grow to 70% or more of the portfolio without you buying a single share. Conversely, a bond rally can push fixed income to a larger share than you intended. Either shift changes how much risk your portfolio actually carries, regardless of what you planned at the start.
This drift is not a sign that something has gone wrong. It is a normal result of assets growing at different rates. Left unchecked, though, a portfolio that started at a moderate risk level can quietly become aggressive or conservative, depending on which assets outperformed. That misalignment can matter a great deal as you approach retirement, when a large drawdown has less time to recover. See how allocation thinking shifts in your 40s and 50s for context on why your target mix deserves regular review.
Small drift is not always worth fixing
A 2% deviation from your target allocation is unlikely to meaningfully change your risk profile. Acting on very small drift adds transaction costs and, in taxable accounts, potential tax liability without a corresponding benefit. Set a reasonable threshold, such as 5 percentage points, before triggering action.
What rebalancing actually does
Rebalancing is the process of selling portions of assets that have grown above your target weight and buying assets that have fallen below it. The goal is to bring your portfolio back to the mix you originally chose, or to an updated mix that still fits your goals.
For example, if your target is 60% stocks and stocks now represent 68% of your portfolio, you would sell enough stock holdings to bring that figure back toward 60%, then direct those proceeds into bonds or whichever asset class is underweight.
This process has a secondary effect that is easy to overlook: it enforces a habit of trimming positions that have grown large and adding to positions that have fallen. That is not market timing. It is a systematic way of maintaining the risk level you chose deliberately. Avoid confusing rebalancing with chasing returns. The goal is not to predict what will outperform next, but to stay consistent with your plan. Investors who skip rebalancing often fall into broader mistakes that quietly erode retirement savings.
Two approaches for triggering a rebalance
There is no universal rule for exactly when to rebalance, but two practical frameworks guide most individual investors.
Calendar-based rebalancing means reviewing your portfolio on a fixed schedule, such as once a year or every six months, and rebalancing at that point if the allocation has drifted. This approach is simple and requires little ongoing monitoring.
Threshold-based rebalancing means setting a tolerance band around each asset class, for instance plus or minus 5 percentage points, and rebalancing only when an allocation breaches that band. If stocks are supposed to be 60% but have grown to 66%, the 5-point threshold is crossed and you act. This approach responds to actual market movement rather than the calendar.
Many investors combine both: they check the portfolio on a set schedule and rebalance only if allocations have drifted beyond a set threshold. This reduces unnecessary trading while preventing extended drift. Pairing rebalancing with a regular contribution strategy, such as the one described in dollar-cost averaging, can also reduce the amount of selling required because new contributions can be directed toward underweight assets.
Record your target allocation
Write down the percentage you want in each asset class: stocks, bonds, cash, and any other category you hold. This is your benchmark. Without a documented target, you cannot measure drift or know when to act.
Check your current allocation
Log in to each account and calculate what percentage of your total portfolio currently sits in each asset class. Include all accounts together, not each one in isolation, since the combined picture is what matters for your overall risk exposure.
Compare actual to target
Subtract your target percentage from your current percentage for each asset class. A positive number means that class is overweight; a negative number means it is underweight. Note which categories have drifted beyond your chosen tolerance band, such as 5 percentage points in either direction.
Decide how to restore the balance
You have two tools: selling overweight assets and buying underweight ones, or directing new contributions toward underweight categories. If you are in an accumulation phase and making regular contributions, new money can often bring allocations back in line without any selling.
Execute the trades and document the date
Place the necessary trades to restore your target allocation. After completing them, record the date and the allocation you restored to. That record becomes the baseline for your next review.
Tax and cost considerations
Rebalancing in a taxable brokerage account involves selling assets that may have appreciated, which can trigger capital gains taxes. Short-term gains, on assets held less than one year, are taxed as ordinary income. Long-term gains, on assets held more than one year, are taxed at lower rates. The exact rates depend on your income and filing status.
One way to limit tax friction is to prioritize rebalancing inside tax-advantaged accounts such as a 401(k) or IRA, where gains are not taxed in the year they occur. When rebalancing is necessary in a taxable account, consider directing new contributions toward underweight assets rather than selling overweight ones. That approach achieves a similar result without generating a taxable event.
Transaction costs are less of a concern than they once were, since many brokers now offer commission-free trading on stocks and ETFs. Still, frequent rebalancing can add up in accounts that still carry transaction fees, so it is worth understanding the cost structure of your accounts before trading.
This article is for informational and educational purposes only. It is not personalized financial, tax, or investment advice. Please consult a qualified financial adviser or tax professional before making decisions about your own portfolio.
Investing Essentials Editorial Team
Investing Essentials Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View author profile