
Coordinating Social Security, Pensions, and Investment Income for a Stable Retirement
Learn how to layer multiple income sources so they complement each other, reduce sequence-of-returns risk, and support a stable standard of living in retirement.
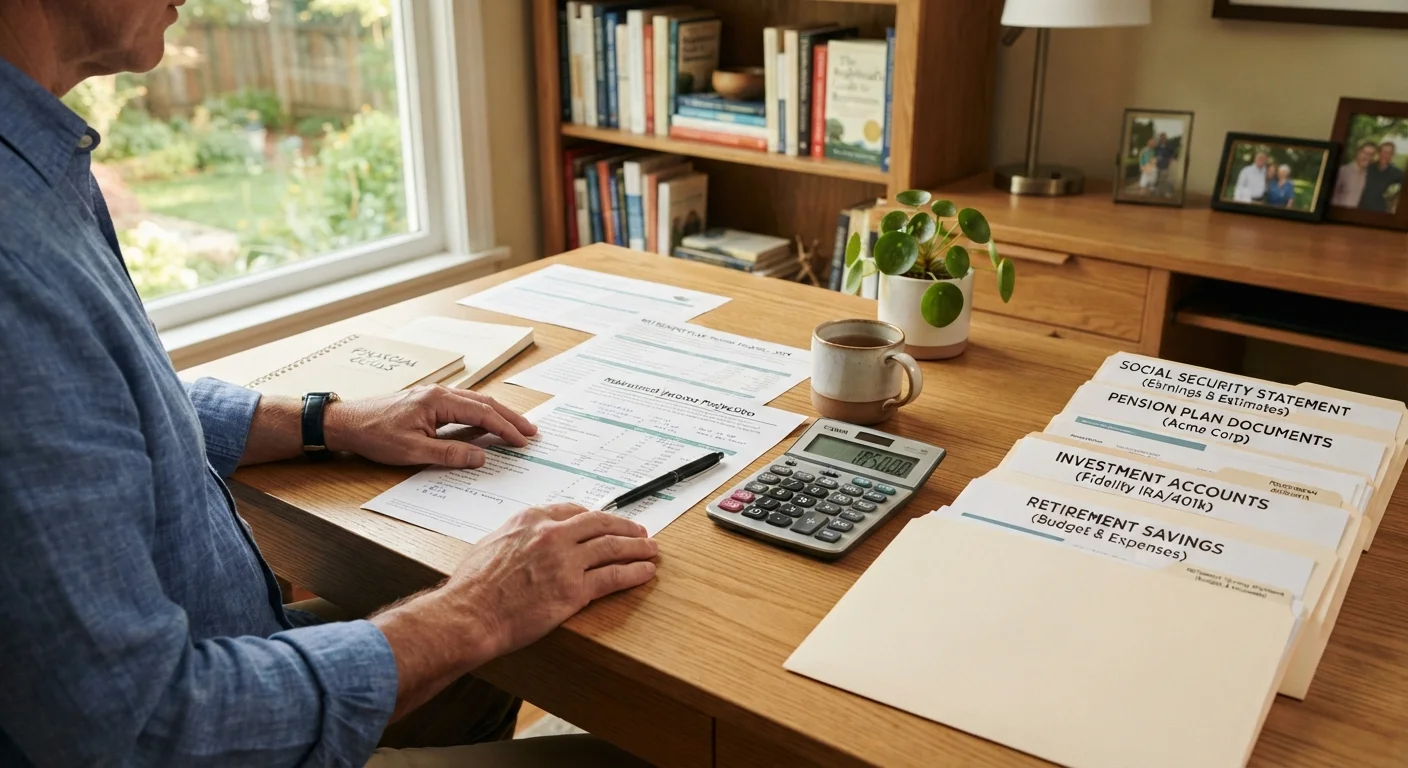
Photo: shapingfinances.com editorial
—— In This Article
Key Takeaways
- Layering guaranteed income from Social Security and pensions reduces reliance on volatile investment withdrawals.
- Delaying Social Security benefits can significantly increase your monthly payment, especially if you live into your 80s.
- Sequence-of-returns risk is most dangerous in the first years of retirement when portfolio withdrawals are largest.
- A drawdown order that preserves tax-advantaged accounts longer can reduce lifetime tax liability.
- Coordinating all income sources requires a written plan, not just a rough mental estimate.
Why coordination matters more than the sum of your parts
Many people approaching retirement think about Social Security, a pension, and an investment portfolio as three separate buckets. In practice, how these sources interact determines whether your income stays stable or becomes vulnerable to taxes, market downturns, or longevity. See Retirement Income Explained: What It Is and Where It Comes From for a grounding overview of how each source works on its own.
The goal of coordination is to cover essential expenses with income that does not depend on market performance, then use investment accounts to fund discretionary spending and absorb inflation over time. When guaranteed income covers your fixed costs, you can afford to leave a growth-oriented portfolio alone during a down market rather than selling at a loss.
Social Security: timing shapes your income floor
Social Security provides a monthly benefit that lasts for life and adjusts for inflation through annual cost-of-living adjustments. The age at which you claim directly sets the payment amount for the rest of your life. Claiming at 62 reduces your benefit relative to your full retirement age (FRA), while waiting until 70 increases it by 8% per year beyond FRA under current rules.
For a married couple, the higher earner delaying to 70 often provides the largest long-term survivor benefit. The lower earner's optimal claiming age depends on health, other income sources, and tax exposure. These decisions interact, so model them together rather than deciding each one in isolation.
Pensions and annuities: structuring guaranteed income
If you have a defined-benefit pension, you typically choose between a single-life annuity and a joint-and-survivor option at retirement. The single-life option pays more monthly but stops at your death, which could leave a spouse without that income. The joint-and-survivor option pays less but continues for a surviving spouse.
Some retirees without pensions consider purchasing an income annuity from an insurance company to create a similar floor. Annuities are insurance contracts and carry their own complexity, including surrender charges, insurer credit risk, and fees. They are not appropriate for everyone, and terms vary widely. A licensed financial adviser can help you weigh whether an annuity fits your situation. For a broader look at passive income options, see Building Passive Income Streams That Can Last Through Retirement.
Investment accounts: managing sequence-of-returns risk
Sequence-of-returns risk is the danger that a sharp market decline in your first few years of retirement, combined with ongoing withdrawals, permanently reduces the portfolio's ability to recover. A portfolio down 30% while you are also withdrawing 4% to 5% annually faces a much harder recovery path than the same portfolio during accumulation.
One approach is to hold one to two years of planned withdrawals in cash or short-term bonds so that you do not need to sell equities during a downturn. This buffer strategy does not eliminate risk, but it reduces the pressure to liquidate at low prices.
Withdrawal order also matters. Spending taxable brokerage accounts first, then tax-deferred accounts such as traditional IRAs, and tax-free accounts such as Roth IRAs last is a common starting framework. Doing so allows tax-deferred and tax-free balances to grow longer. However, the right sequence depends on your tax bracket, Required Minimum Distribution (RMD) obligations beginning at age 73 under current law, and other income. The Making Your Retirement Savings Last: A Step-by-Step Drawdown Framework covers this decision in detail.
Building a written coordination plan
A written plan connects each income source to a spending category and a timeline. It should document when you will claim Social Security, which pension option you selected, how much you expect from investment withdrawals in each phase of retirement, and how you will adjust if any source changes.
People who are building a retirement plan after 45 often underestimate how much pre-retirement debt affects their income needs. Carrying a mortgage or high-interest debt into retirement raises your fixed expense floor and reduces the buffer that guaranteed income provides. See Managing Debt Strategically in the Years Leading Up to Retirement for strategies to address this before you stop working.
Review the plan at least once a year or when a major change occurs, such as a job change, a spouse's health event, or a significant market move. This article is general financial information and is not personalised financial, tax, or legal advice. Consult a licensed financial adviser, tax professional, or attorney before making decisions specific to your situation.
This article is for general informational and educational purposes only and does not constitute personalised financial, tax, investment, or legal advice. Consult a qualified, licensed professional before making any decisions about your retirement income strategy.
Retirement Income Editorial Team
Retirement Income Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View author profile