
Life Insurance in Retirement: When Keeping a Policy Still Makes Sense
Many retirees drop life insurance, but for some households it still serves a purpose. Explore the scenarios where keeping coverage may be worth the premium.
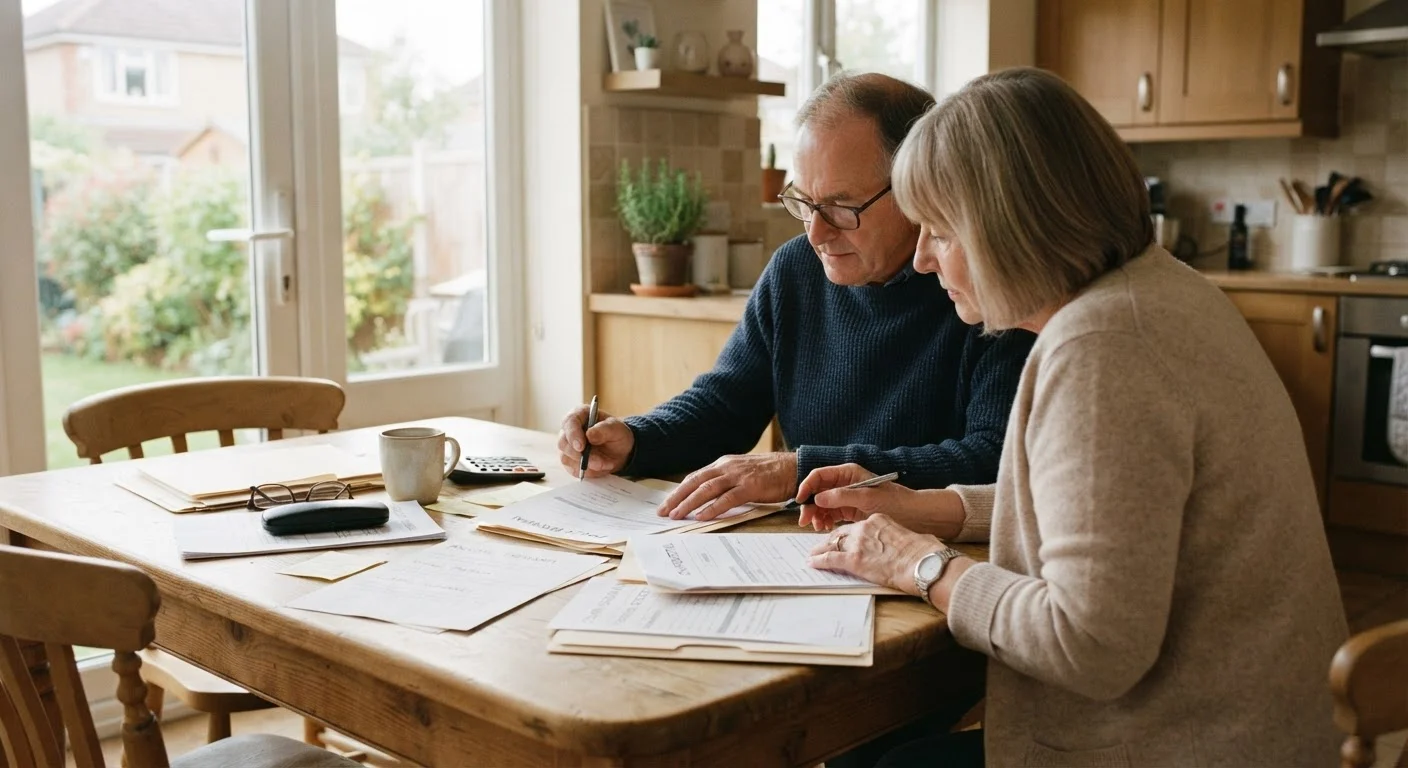
Photo: shapingfinances.com editorial
—— In This Article
Key Takeaways
- Life insurance in retirement is not automatically unnecessary; several financial scenarios justify keeping a policy.
- Permanent policies with cash value can fund estate planning goals or offset long-term care costs.
- Premiums paid in retirement reduce the income available for living expenses, so the math matters.
- Survivor income needs and outstanding debts are the clearest reasons to maintain coverage.
- A licensed financial adviser can help you weigh the cost against the specific protection a policy provides.
Replaces pension income lost when the insured dies
Single-life pension payouts stop at death, leaving the surviving spouse without that income stream. A life insurance benefit can substitute for it without requiring the survivor to draw down savings prematurely.
Provides liquidity for estate tax obligations
For estates that exceed the federal estate tax exemption, a death benefit held in an irrevocable trust can pay the tax bill without forcing a sale of illiquid assets like real estate or a family business.
Cash value in permanent policies can fund retirement needs
Whole life and universal life policies accumulate cash value that the policyholder can borrow against or withdraw, giving a retiree a supplemental source of funds for healthcare or other costs.
Can offset long-term care costs through hybrid policies
Some permanent policies include a long-term care rider that allows the death benefit to be accessed early to cover nursing home or home care expenses, reducing reliance on other assets.
Covers outstanding debts a survivor would inherit
If a retiree still carries a mortgage or has co-signed obligations, a death benefit can clear those debts and protect the surviving spouse from forced asset liquidation.
Premiums reduce available retirement income
Life insurance premiums at age 65 or older are substantially higher than at younger ages. Paying them out of a fixed retirement income can meaningfully reduce the funds available for daily living expenses.
Coverage may no longer match the underlying need
The financial obligations life insurance was originally purchased to cover, such as a mortgage or dependent children's expenses, often no longer exist by retirement. Continuing the policy without a clear purpose produces no financial benefit.
Term policies expire and become unrenewable at affordable rates
A retiree whose term policy ends after a health decline may find replacement coverage prohibitively expensive or unavailable, which makes planning ahead essential but does not justify keeping a policy past its useful purpose.
Cash value growth is not always competitive
The internal rate of return on a permanent policy's cash value component is often lower than what a diversified investment portfolio might produce over the same period, particularly for policies with high internal costs.
Complexity can obscure true cost
Permanent policies involve fees, surrender charges, and loan interest that make the actual cost of coverage harder to assess than a simple premium figure suggests. Retirees on fixed incomes benefit from straightforward cost structures.
Why retirees reconsider life insurance
The conventional logic says life insurance is for working years: it replaces income if the breadwinner dies before the family is financially independent. By retirement, the thinking goes, savings and Social Security fill that role. That logic holds for many households, but not all of them.
Several financial circumstances persist into retirement that life insurance is well-positioned to address. A spouse who relies on a pension that does not offer a survivor benefit, a large estate subject to federal estate tax, or a permanent policy already carrying substantial cash value are all situations where cancellation may cost more than continuation. Understanding these scenarios clearly is the starting point for an honest cost-benefit review.
For a broader look at how insurance products interact with retirement income, see retirement insurance explained. Before reviewing the pros and cons below, bear in mind that this article is general information, not personalised financial or insurance advice. Coverage terms, premiums, and eligibility vary by provider and by individual circumstances.
Where life insurance still earns its premium
Replaces pension income lost when the insured dies
Single-life pension payouts stop at death, leaving the surviving spouse without that income stream. A life insurance benefit can substitute for it without requiring the survivor to draw down savings prematurely.
Provides liquidity for estate tax obligations
For estates that exceed the federal estate tax exemption, a death benefit held in an irrevocable trust can pay the tax bill without forcing a sale of illiquid assets like real estate or a family business.
Cash value in permanent policies can fund retirement needs
Whole life and universal life policies accumulate cash value that the policyholder can borrow against or withdraw, giving a retiree a supplemental source of funds for healthcare or other costs.
Can offset long-term care costs through hybrid policies
Some permanent policies include a long-term care rider that allows the death benefit to be accessed early to cover nursing home or home care expenses, reducing reliance on other assets.
Covers outstanding debts a survivor would inherit
If a retiree still carries a mortgage or has co-signed obligations, a death benefit can clear those debts and protect the surviving spouse from forced asset liquidation.
The strongest case for keeping life insurance in retirement comes down to income replacement for a surviving spouse. If one partner receives a pension with a single-life payout, that income stops at death. A life insurance death benefit can bridge the gap. This is especially relevant for households where Social Security is also structured around one partner's higher earning record, since the survivor collects only the larger of the two benefits, losing the smaller one entirely.
Permanent life insurance policies, such as whole life or universal life, accumulate a cash value component over time. That cash value can be accessed through loans or withdrawals during retirement to cover expenses, including long-term care costs. Some hybrid life/long-term care policies are specifically structured for this dual purpose.
For higher-net-worth households, life insurance held inside an irrevocable life insurance trust (ILIT) can provide liquidity to pay estate taxes without forcing heirs to sell assets such as a family business or real estate. The federal estate tax exemption is subject to legislative change, so households with significant assets should track this threshold with a qualified estate attorney.
The genuine costs and drawbacks
Premiums reduce available retirement income
Life insurance premiums at age 65 or older are substantially higher than at younger ages. Paying them out of a fixed retirement income can meaningfully reduce the funds available for daily living expenses.
Coverage may no longer match the underlying need
The financial obligations life insurance was originally purchased to cover, such as a mortgage or dependent children's expenses, often no longer exist by retirement. Continuing the policy without a clear purpose produces no financial benefit.
Term policies expire and become unrenewable at affordable rates
A retiree whose term policy ends after a health decline may find replacement coverage prohibitively expensive or unavailable, which makes planning ahead essential but does not justify keeping a policy past its useful purpose.
Cash value growth is not always competitive
The internal rate of return on a permanent policy's cash value component is often lower than what a diversified investment portfolio might produce over the same period, particularly for policies with high internal costs.
Complexity can obscure true cost
Permanent policies involve fees, surrender charges, and loan interest that make the actual cost of coverage harder to assess than a simple premium figure suggests. Retirees on fixed incomes benefit from straightforward cost structures.
Premiums at older ages are not trivial. A healthy 65-year-old can pay several thousand dollars annually for a permanent policy with a meaningful death benefit, and those premiums come directly out of retirement income. If the underlying financial need the policy was bought to solve no longer exists, that cost produces no return.
For retirees whose retirement income is already sufficient for a surviving spouse, whose debts are paid off, and whose estate falls well below the taxable threshold, maintaining life insurance can be a misallocation of limited cash flow. The premium dollars might generate more security invested or held in liquid savings.
Term policies, the most affordable type during working years, eventually expire. If a term policy ends during retirement and the insured's health has declined, obtaining new coverage at an affordable premium may not be possible. This is a constraint, not a reason to keep a policy that no longer serves a purpose, but it is worth factoring into any decision made before the term lapses.
See insurance gaps that quietly drain retirement savings for a fuller picture of where uninsured costs tend to catch retirees off guard.
Specific situations worth examining closely
Pension survivor benefits and life insurance overlap
Some defined benefit pensions offer a joint-and-survivor annuity option that continues payments to a spouse after the retiree's death, though usually at a reduced amount. If your pension already includes a survivor benefit, that reduces the income gap life insurance would need to fill. Review your specific pension election documents carefully, and consider whether the survivor benefit amount is adequate before purchasing or continuing a policy.
Pension recipients with no survivor benefit option, or those who chose a higher single-life payout, have a concrete income gap that does not self-correct. If that pension represents the household's primary income, a life insurance death benefit is one of the few tools that can replace it. The gaps that come with defined benefit pension income deserve careful attention for anyone in this situation.
Business owners who have not yet completed a succession plan may need a policy to fund a buy-sell agreement or to provide liquidity for estate settlement. Those obligations can outlast formal retirement from day-to-day operations.
Adults who are still carrying significant debt into retirement, whether a mortgage or co-signed obligations, also have a legitimate coverage need. A death benefit that clears those obligations protects a surviving spouse from being forced to liquidate assets under pressure.
On the other side, a retiree with a well-funded defined contribution account, no dependents, a paid-off home, and a modest estate has very little that life insurance adds. The premium cost at that point is difficult to justify on purely financial grounds.
This article is for informational and educational purposes only and does not constitute personalised financial, insurance, or legal advice. Insurance coverage terms, premiums, exclusions, and eligibility depend on the provider and on individual circumstances. Consult a licensed insurance agent or a qualified financial adviser before making decisions about your own coverage.
Retirement Insurance Editorial Team
Retirement Insurance Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View author profile