
Long-Term Care Insurance: What It Covers and Who Typically Needs It
Long-term care insurance can help cover nursing home and home care costs. Here is what the coverage includes and the factors that shape eligibility.
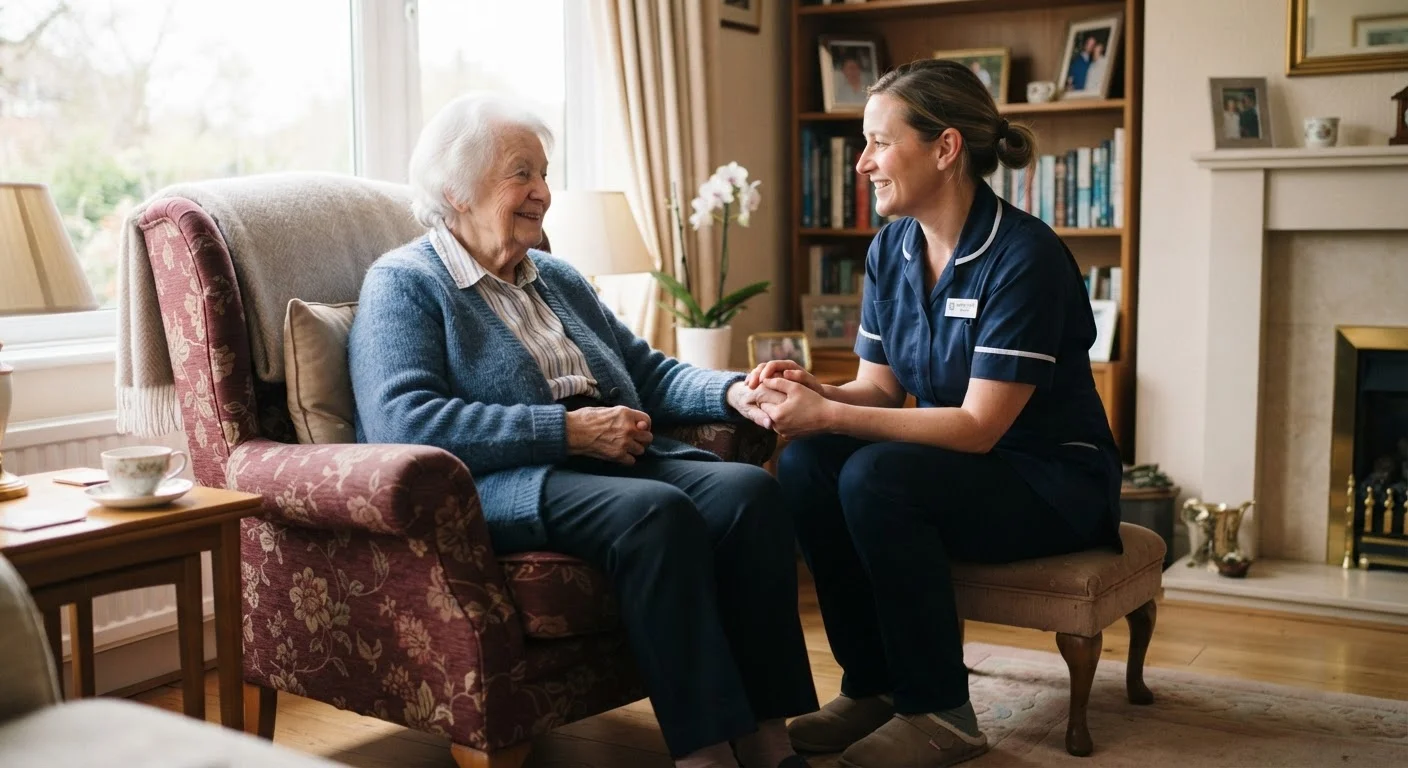
Photo: shapingfinances.com editorial
—— In This Article
Key Takeaways
- Long-term care insurance covers custodial care costs that Medicare generally does not pay for.
- Benefits are triggered when a person cannot perform two or more basic daily activities without help.
- Premiums are lower and approval is more likely when a policy is purchased before health declines.
- Coverage can apply to home care, assisted living, adult day care, and nursing home stays.
- Policy terms vary widely; reading the actual contract is the only way to confirm what is and is not covered.
What long-term care insurance actually covers
Long-term care insurance pays for assistance with the physical and cognitive tasks of everyday life, not for medical procedures or hospital stays. Covered settings typically include:
- Care at home provided by a licensed home health aide or home care agency
- Assisted-living facilities, where residents receive help with daily activities while maintaining some independence
- Memory care units for people with dementia or Alzheimer's disease
- Skilled nursing facilities, for extended stays that go beyond what Medicare will fund
- Adult day care programs that provide supervision and social support outside the home during daytime hours
Policies pay benefits in one of two ways. A reimbursement policy pays back documented care expenses up to a daily or monthly limit. An indemnity (cash benefit) policy pays the full benefit amount once eligibility is confirmed, regardless of what actual care costs. The distinction matters because reimbursement policies require receipts and approved providers, while indemnity policies give more flexibility, including the option to pay a family member who provides care.
Most policies also include an inflation protection option that increases the benefit amount over time. Without it, a benefit that seems adequate today may fall short of actual costs in 20 years. Uncovered care costs are among the most common financial surprises retirees face, and LTCI is one tool designed to address that gap.
How benefits are triggered
An insurer will not begin paying benefits simply because a policyholder has aged or entered a care facility. Two standard triggers exist:
- ADL deficit: A licensed health professional must certify that the insured cannot perform at least two of six Activities of Daily Living without substantial assistance. The six ADLs are bathing, dressing, eating, continence, toileting, and transferring (moving from a bed to a chair, for example).
- Cognitive impairment: A diagnosis of severe cognitive impairment, such as Alzheimer's disease or another form of dementia, can independently trigger benefits even if ADL function is still partially intact.
Most policies also include an elimination period, which works like a deductible measured in time rather than dollars. Elimination periods of 30, 60, or 90 days are common. During that window, the policyholder pays for care out of pocket before the insurance benefit begins. A longer elimination period lowers the premium but requires more financial reserves to cover the gap.
Policy language defines your actual coverage
Insurance policy documents vary significantly in how they define ADLs, cognitive impairment, and approved care settings. A policy that appears similar on a summary sheet may have materially different benefit triggers in its full contract language. Always read the actual policy document, not just the brochure, and ask a licensed agent to clarify any terms that are not clear.
Understanding these triggers matters when comparing policies. Some older policies use stricter ADL definitions or require all six ADLs to be impaired. Confirm the exact language in any policy document before signing.
Who typically needs this coverage
Not everyone will need long-term care, but the financial exposure for those who do is substantial. The U.S. Department of Health and Human Services has estimated that roughly 70% of people turning 65 will need some form of long-term care in their lifetimes. The duration and intensity vary widely, from a few months of home assistance after surgery to several years of full-time memory care.
People in the following situations often benefit most from evaluating LTCI:
- Those with a family history of chronic illness, dementia, or conditions requiring extended care
- Individuals without a spouse or adult children who could provide informal unpaid care
- Households where a surviving spouse would face financial strain if care costs depleted joint assets
- People with moderate assets who have too much wealth to qualify for Medicaid long-term care benefits but not enough to self-fund years of facility care
People with very limited assets may ultimately rely on Medicaid for long-term care, and those with very large estates may choose to self-insure. LTCI tends to be most useful for the wide middle range.
Several common assumptions about LTCI deserve scrutiny, including the belief that Medicare will handle extended care costs. Pension income can help, but it rarely covers the full cost of facility-based care, which can exceed $90,000 per year in many U.S. markets.
Policy structure and what shapes premiums
LTCI premiums depend on several factors set at the time of application. Age is the most straightforward: a 55-year-old in good health will generally pay considerably less than a 65-year-old applying for the same benefit amount. Health status at application is evaluated through medical underwriting, and pre-existing conditions can result in exclusions, higher rates, or denial.
Three policy design choices have the largest effect on what a premium costs:
- Daily or monthly benefit amount: The maximum the policy will pay per day or per month for covered care. Higher limits cost more.
- Benefit period: How long the policy will pay once benefits begin. A three-year benefit period carries a lower premium than a five-year period.
- Inflation protection: Compound inflation protection, which increases the benefit at a fixed percentage each year, adds to premium cost but preserves purchasing power over time.
Hybrid policies, which combine LTCI benefits with a life insurance or annuity component, have become more common. They address a concern many buyers have about traditional LTCI: if care is never needed, premiums appear to go to waste. With a hybrid product, unused long-term care benefits typically remain as a death benefit or returned premium. Life insurance in retirement and LTCI can overlap in hybrid form, so understanding the mechanics of both is worth the time for anyone near or in retirement.
Retirement insurance broadly covers multiple product types, and LTCI is one piece of a larger picture. A licensed insurance agent or a fee-only financial planner can model how different policy structures interact with your other retirement income sources before you make a decision.
This article is for general informational purposes only and is not personalized financial, insurance, or legal advice. Coverage terms, exclusions, and premiums vary by provider and by state. Consult a licensed insurance professional or qualified financial adviser before making decisions about your own situation.
Frequently Asked Questions
Retirement Insurance Editorial Team
Retirement Insurance Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View author profile