
The Language of Retirement: Key Terms Every Saver Should Understand
Defined Benefit, RMD, vesting schedule: a plain-language reference to the retirement planning terms you'll encounter and what they actually mean.
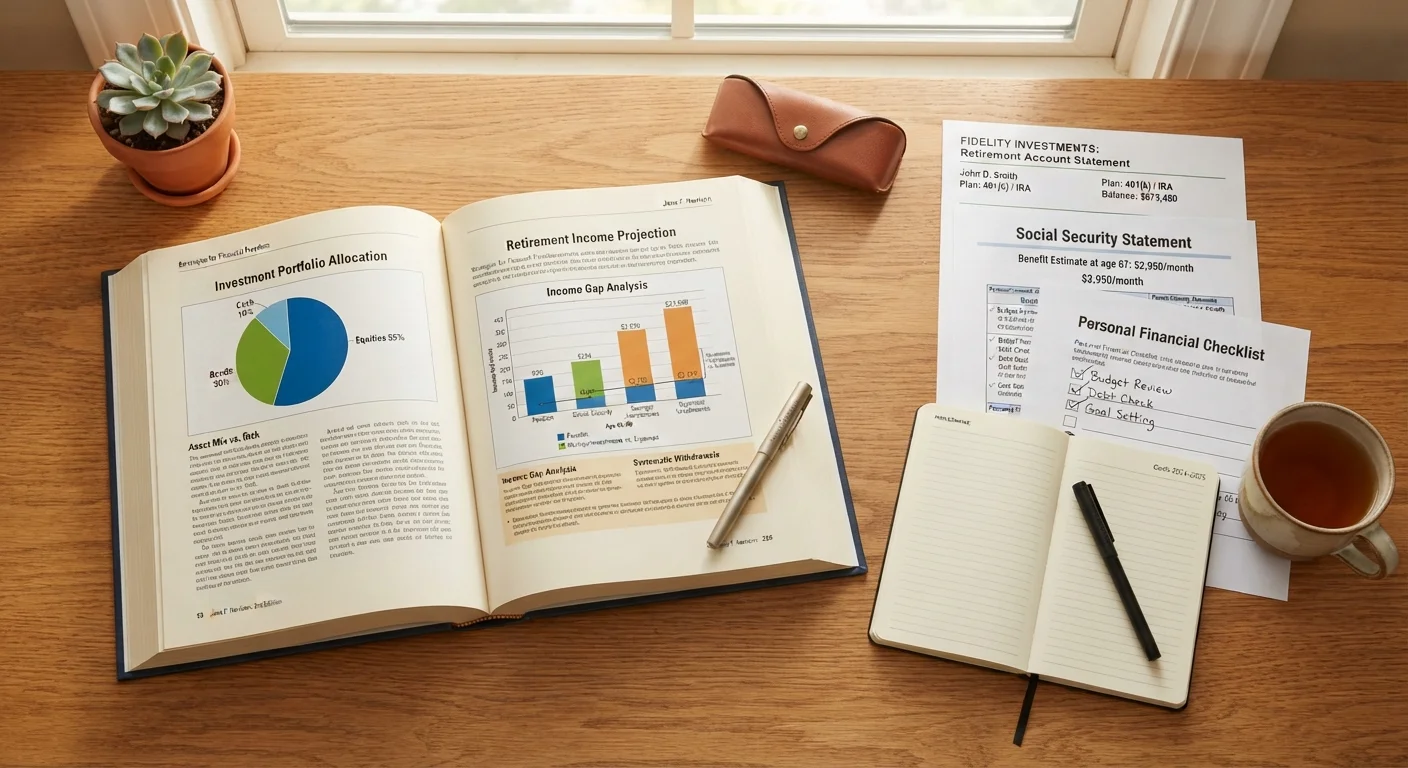
Photo: shapingfinances.com editorial
—— In This Article
Why the vocabulary matters
Retirement planning documents, account statements, and employer benefits packets are dense with specialized language. Missing the meaning of a single term, say, the difference between a vesting schedule and a contribution limit, can translate into real money left on the table or tax penalties you did not expect. This reference covers the terms you are most likely to encounter, defined plainly so you can read the actual documents with confidence.
For a broader view of how these pieces fit together, see Retirement Income Explained and the Retirement Income hub.
| 2024 401(k) standard contribution limit | $23,000 (IRS Notice 2023-75) |
| 2024 401(k) catch-up limit (age 50+) | $7,500 additional (IRS Notice 2023-75) |
| 2024 IRA contribution limit | $7,000 ($8,000 if age 50+) (IRS Notice 2023-75) |
| RMD starting age (born 1951 or later) | Age 73 (SECURE 2.0 Act (2022)) |
| Full Retirement Age for those born 1960+ | Age 67 (Social Security Administration) |
| Early withdrawal penalty rate | 10% plus ordinary income tax (IRS Publication 590-B) |
Account types and contribution rules
401(k): A workplace retirement savings plan under IRS Section 401(k). Contributions come from pre-tax wages, reducing your taxable income in the year you contribute. Earnings grow tax-deferred until withdrawal.
Traditional IRA (Individual Retirement Account): A personal retirement account funded with pre-tax or after-tax dollars depending on income and whether you have a workplace plan. Withdrawals in retirement are taxed as ordinary income.
Roth IRA: Funded with after-tax dollars. Qualified withdrawals in retirement are tax-free. Income limits apply; consult the current IRS Publication 590-A for the phase-out thresholds that apply to your filing status.
Catch-up contribution: An extra amount the IRS allows savers aged 50 and older to contribute beyond the standard annual limit. For 2024, the catch-up amount for 401(k) plans is $7,500 on top of the standard $23,000 limit. For IRAs, it is $1,000 on top of the standard $7,000 limit. These figures are indexed and can change; verify against the IRS website for the current tax year.
Contribution limit: The maximum dollar amount the IRS permits you to deposit into a tax-advantaged account within a given tax year. Exceeding the limit triggers an excise tax.
Employer match: The amount an employer adds to your 401(k) as a percentage of your own contribution, up to a defined threshold. A common structure is 50% of employee contributions up to 6% of salary. Failing to contribute enough to capture the full match is, in effect, leaving compensation unpaid.
Vesting, distributions, and penalties
Vesting schedule: The timeline over which you gain full ownership of employer-contributed funds in a workplace plan. You always own 100% of your own contributions immediately. Employer contributions become yours either all at once (cliff vesting) or gradually over several years (graded vesting). Leaving a job before full vesting means forfeiting unvested employer funds.
Required Minimum Distribution (RMD): The minimum amount the IRS requires you to withdraw annually from most tax-deferred retirement accounts once you reach a specified age. Under current law (SECURE 2.0 Act), that age is 73 for most account holders. Roth IRAs do not have RMDs during the original owner's lifetime. Failing to take an RMD triggers a 25% excise tax on the amount you should have withdrawn (reduced to 10% if corrected promptly).
Early withdrawal penalty: A 10% federal tax penalty applied when you take a distribution from a tax-deferred retirement account before age 59.5, in addition to ordinary income tax on the amount withdrawn. Certain exceptions apply, including disability, substantially equal periodic payments (SEPP/72(t)), and qualified birth or adoption.
Rollover: The transfer of funds from one retirement account to another without triggering immediate taxes. A direct rollover moves funds institution to institution; an indirect rollover gives you the funds for up to 60 days before redeposit, with the employer withholding 20% for potential taxes in the meantime.
Benefit types and income concepts
Defined Benefit (DB) plan: A traditional employer pension that promises a specific monthly payment in retirement, calculated using a formula that typically factors in years of service and final average salary. The employer bears the investment risk. Fewer private-sector employers offer DB plans today, though they remain common in government and some union positions.
Defined Contribution (DC) plan: A retirement plan, such as a 401(k), in which contributions are defined but the eventual balance depends on investment performance. The employee bears the investment risk. Most private-sector retirement saving now occurs through DC plans.
Full Retirement Age (FRA): The age at which you qualify for 100% of your Social Security retirement benefit, as calculated by the Social Security Administration. FRA is 67 for anyone born in 1960 or later. Claiming earlier reduces your benefit; claiming later (up to age 70) increases it. For more detail on how claiming age affects your benefit, see Social Security Benefits: A Plain-Language Guide for Pre-Retirees.
Asset allocation: The distribution of your investment portfolio across asset classes such as stocks, bonds, and cash equivalents. Allocation affects both potential return and risk exposure. The appropriate mix generally shifts toward less volatile assets as retirement approaches, though individual circumstances vary. For foundational investing concepts, the Investing Essentials hub is a useful companion reference.
Sequence of returns risk: The risk that poor investment returns early in retirement, when you are drawing down your portfolio, can permanently reduce how long your money lasts, even if average returns over the full period are acceptable.
For guidance on insurance products that intersect with retirement income, see Retirement Insurance Explained and Medicare Parts A, B, C, and D.
This article is for general informational and educational purposes only and is not personalized financial, tax, legal, or investment advice. Tax rules and contribution limits change; always verify figures with the IRS or a qualified financial professional before making decisions about your own accounts.
Retirement Planning Editorial Team
Retirement Planning Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View author profile