
Social Security Benefits: A Plain-Language Guide for Pre-Retirees
Learn how Social Security benefits are calculated, when you can claim them, and how your claiming age affects your monthly payments for life.
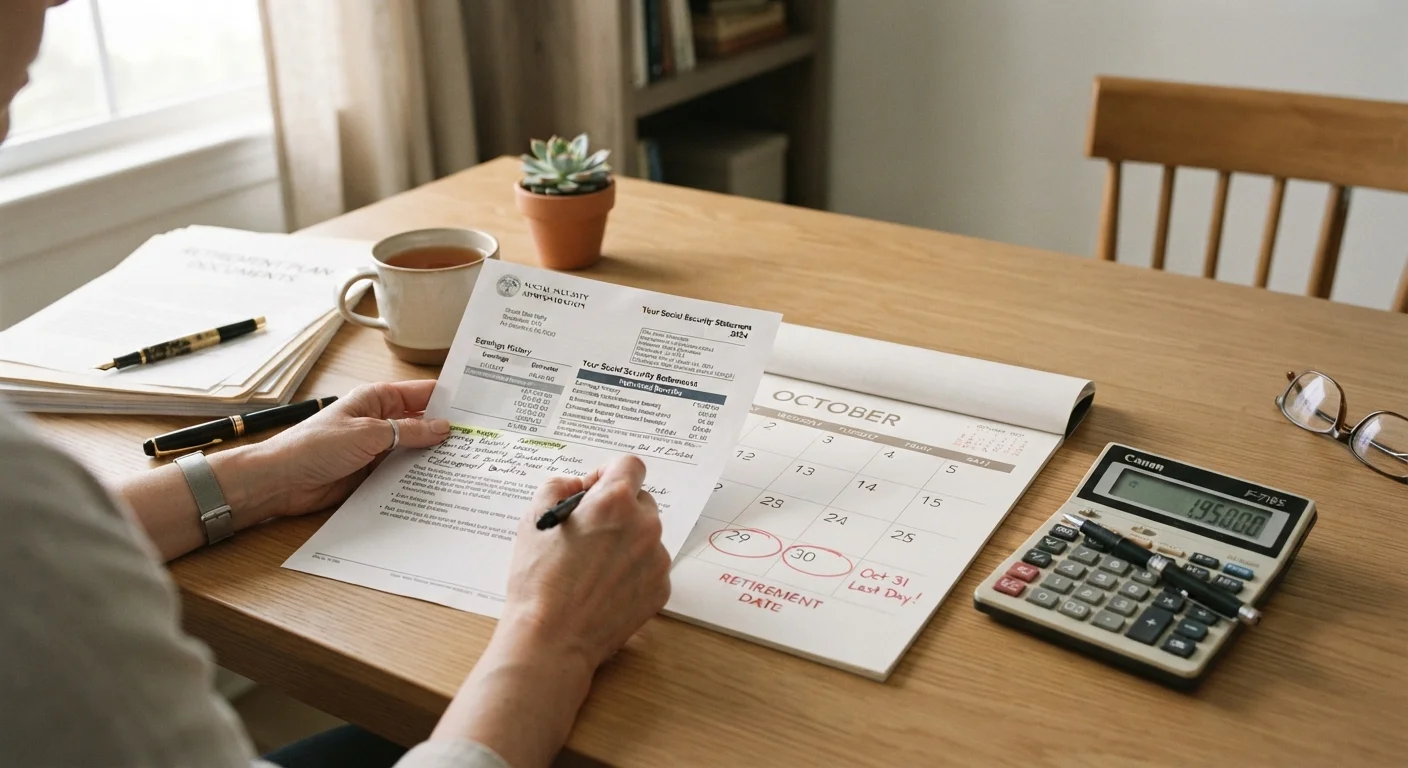
Photo: shapingfinances.com editorial
—— In This Article
Key Takeaways
- Social Security calculates your benefit using your 35 highest-earning years, adjusted for wage inflation.
- You can claim as early as age 62, but doing so permanently reduces your monthly benefit.
- Waiting until age 70 produces the largest possible monthly payment, with delayed credits of about 8% per year after full retirement age.
- Spousal benefits can reach up to 50% of your partner's full retirement benefit.
- Social Security is designed to replace only a portion of pre-retirement income, so other savings and income sources matter.
How Social Security benefits are calculated
Social Security retirement benefits are based on your personal earnings record, not a flat rate. The Social Security Administration (SSA) tracks your taxable wages and self-employment income throughout your working life. When the time comes to calculate your benefit, the SSA uses your 35 highest-earning years, each adjusted upward to reflect wage growth over time.
That process produces a figure called your Average Indexed Monthly Earnings (AIME). The SSA then runs the AIME through a formula that applies progressively lower percentages at higher income levels, producing your Primary Insurance Amount (PIA). The PIA is the monthly payment you would receive if you claim exactly at your full retirement age (FRA).
If you have worked fewer than 35 years, the SSA counts zero-earning years in the average, which lowers your AIME and, in turn, your monthly payment. Working additional years with higher earnings can replace earlier low-earning years and raise your benefit.
Primary Insurance Amount (PIA)
The monthly Social Security benefit you receive if you claim exactly at your full retirement age. Early or late claiming adjusts this figure up or down.
Average Indexed Monthly Earnings (AIME)
The monthly average of your 35 highest-earning years, with past wages adjusted for wage growth. The SSA uses this figure to calculate your PIA.
Full retirement age (FRA)
The age at which you are entitled to your full PIA with no reduction. It ranges from 66 to 67 depending on your birth year.
Delayed retirement credits
The additional percentage added to your benefit for each year you delay claiming past your full retirement age, up to age 70. The credit is about 8% per year.
Cost-of-living adjustment (COLA)
An annual increase to Social Security benefits tied to a measure of inflation. It helps maintain purchasing power over a long retirement.
Spousal benefit
A Social Security benefit available to a spouse or qualifying ex-spouse, worth up to 50% of the worker's PIA, depending on the claimant's age at filing.
You can review your estimated benefits at any time through your personal My Social Security account at ssa.gov. The SSA also mails paper statements to workers aged 60 and older who have not yet claimed and do not have an online account.
This article is for general educational purposes only and is not personalized financial, tax, or legal advice. Consult a qualified financial adviser or tax professional for guidance specific to your situation.
When you can start claiming
You can begin receiving Social Security retirement benefits as early as age 62. Your full retirement age, the age at which you receive your full PIA, depends on when you were born. For everyone born in 1960 or later, the FRA is 67. For those born between 1943 and 1954, it is 66. Birth years between 1955 and 1959 have FRAs that step up in two-month increments.
The other boundary is age 70. The SSA does not increase benefits for delaying past 70, so there is no financial reason to wait beyond that age once you have decided to claim.
For a fuller picture of how Social Security fits alongside other income sources, see Retirement Income Explained: What It Is and Where It Comes From.
How your claiming age affects your monthly payment
The age at which you claim is one of the most consequential decisions in retirement planning because it permanently sets your monthly benefit (adjusted annually for inflation through cost-of-living adjustments).
Claiming before your FRA reduces the benefit by a fixed percentage for each month claimed early. The reduction is approximately 5/9 of 1% per month for the first 36 months before FRA, and 5/12 of 1% for each additional month. For a person with an FRA of 67 who claims at 62, that adds up to a reduction of about 30%.
Waiting beyond your FRA earns delayed retirement credits. The SSA adds roughly 8% to your benefit for each full year you defer past FRA, up to age 70. A person with an FRA of 67 who waits until 70 receives a benefit roughly 24% higher than their PIA.
Use the SSA's free online tools
The Social Security Administration offers a retirement estimator and a full benefits calculator at ssa.gov. Creating a My Social Security account lets you see your actual earnings record, check for errors, and model different claiming ages before making any decisions. Reviewing your record for accuracy is worth doing well before you are ready to claim.
There is no universally correct age to claim. A person in good health who expects a long retirement may collect more in lifetime benefits by waiting. Someone with significant health concerns or financial need may be better served by claiming earlier. A licensed financial planner can model your specific situation.
For guidance on how to layer Social Security with other income, see Coordinating Social Security, Pensions, and Investment Income for a Stable Retirement.
Spousal and survivor benefits
Social Security extends benefits beyond individual workers. A spouse who has little or no earned benefit of their own may claim a spousal benefit worth up to 50% of their partner's PIA, provided both have reached their FRAs. Claiming the spousal benefit early reduces it on the same schedule that applies to individual benefits.
Survivor benefits work differently. A widow or widower can receive up to 100% of the deceased spouse's benefit, starting as early as age 60 (or 50 with a qualifying disability). Because survivor benefits use different rules from spousal benefits, couples often plan their claiming ages together to maximize what the surviving spouse will eventually receive.
Divorced spouses may also qualify for benefits based on an ex-spouse's record if the marriage lasted at least 10 years and the claimant has not remarried. The ex-spouse's benefit is not affected.
If you are in your 50s and want to audit your broader financial preparedness, Insuring Your Retirement: A Step-by-Step Coverage Review for People in Their 50s walks through coverage gaps worth addressing before you retire.
How Social Security fits into your broader retirement income
Social Security was designed to replace a portion of pre-retirement income, not all of it. The exact replacement rate varies by earnings level: lower earners see a higher percentage replaced, higher earners a lower one. For most people, Social Security alone will not cover all living expenses in retirement.
That gap is why workplace pensions, personal savings, and investment accounts matter. If you are newer to building those pieces, Retirement Planning From Scratch: A Complete Primer for Adults Starting Late covers the core accounts and strategies worth knowing. For building savings habits that accelerate your retirement fund, see practical saving strategies.
Medicare eligibility begins at 65, which is separate from Social Security's earliest claiming age of 62. If you claim Social Security before 65, you will need to arrange your own health coverage for the intervening years. For a clear breakdown of what Medicare covers, Medicare Parts A, B, C, and D: A Plain-Language Breakdown is a useful companion.
Understanding the terminology used across all these systems also helps. The Language of Retirement: Key Terms Every Saver Should Understand is a plain-language reference for the concepts you will encounter.
Frequently Asked Questions
Retirement Income Editorial Team
Retirement Income Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View author profile