
Catch-Up Contributions Explained: What They Mean for Your Retirement Savings
Understand how catch-up contributions work for adults over 50 and why they can meaningfully increase your retirement fund in fewer years.
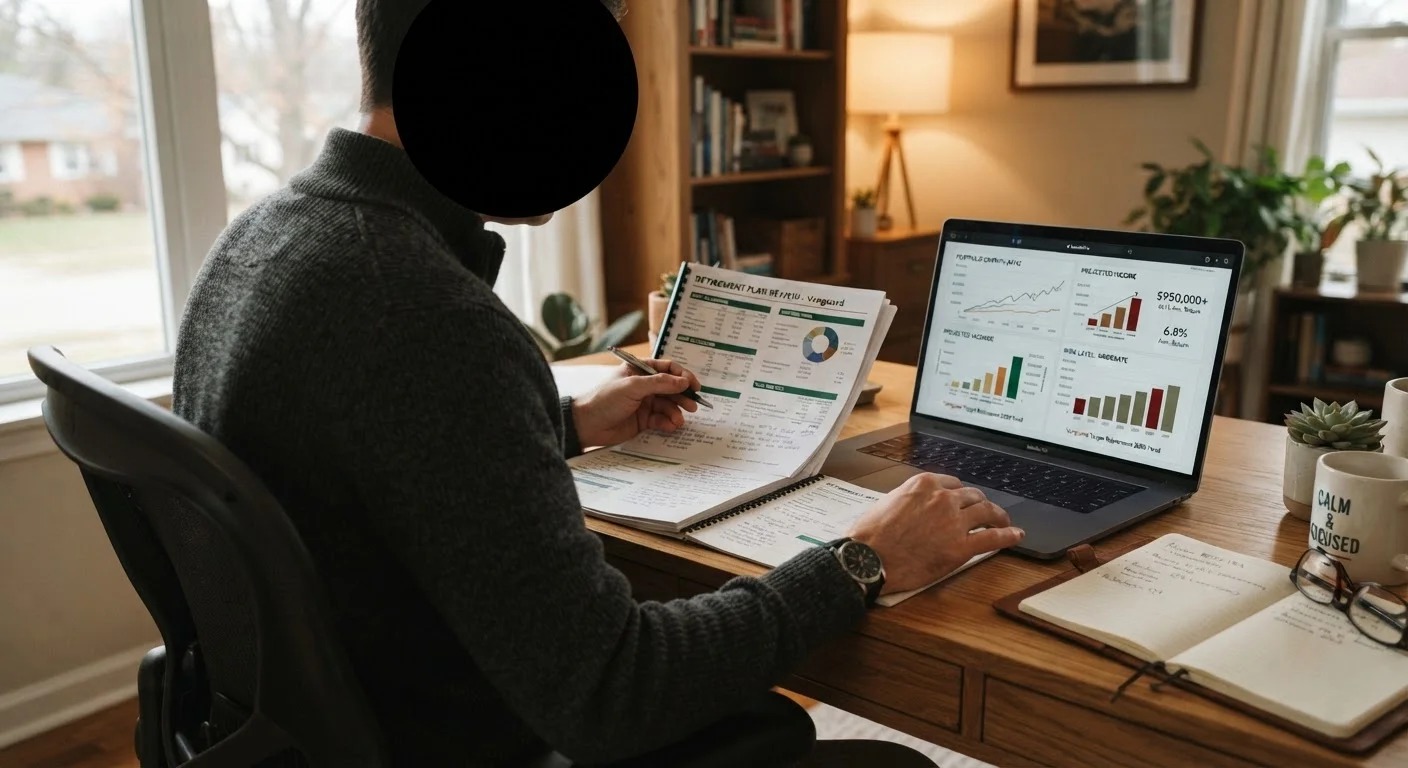
Photo: shapingfinances.com editorial
—— In This Article
Key Takeaways
- Workers 50 and older can contribute more than the standard annual limit to 401(k)s and IRAs.
- The IRS adjusts catch-up limits periodically; confirm current figures before making contribution decisions.
- Even a few years of maximized catch-up contributions can close a meaningful savings gap.
- Employer matching typically applies only to the standard contribution, not the catch-up portion.
- SECURE 2.0 introduced a higher catch-up tier for workers aged 60 to 63 in employer plans.
How catch-up contributions work
Each year the IRS sets a ceiling on how much workers can contribute to retirement accounts. For 2024, the standard 401(k) deferral limit is $23,000 and the IRA contribution limit is $7,000. Workers who are 50 or older can contribute an additional $7,500 to a 401(k) or similar employer plan, bringing their total to $30,500. The IRA catch-up is $1,000, for a combined IRA ceiling of $8,000.
These numbers matter because they represent legal contribution room, not a guarantee of tax savings or investment growth. Whether contributions go in pre-tax, after-tax, or into a Roth account affects how withdrawals are taxed in retirement. A tax professional can help you decide which allocation fits your situation.
If you are building your baseline knowledge of retirement accounts and want context on the full range of strategies available to late starters, see the complete retirement planning primer.
Update your contribution election actively
Catch-up eligibility does not trigger automatically when you turn 50. You must log into your employer plan portal or submit a new deferral form to increase your contribution to the higher limit. Set a calendar reminder each January to confirm your election matches the current IRS limits.
Why the extra room matters in your 50s
Compounding works by generating returns on previous returns. A worker who starts saving at 25 has decades for that process to build. Someone starting or restarting serious contributions at 50 has roughly 15 years before a typical retirement age. Catch-up contributions do not restore lost compounding time, but they do increase the principal that earns returns over those remaining years.
An extra $7,500 per year in a 401(k), contributed consistently from age 50 to 65, adds $112,500 in raw contributions alone before any growth. How much that grows depends on investment choices and market conditions, and past performance does not guarantee future results. Still, the math confirms that larger annual contributions do increase the account balance available at retirement.
$30,500
2024 maximum 401(k) contribution, age 50+
The IRS sets this combined standard-plus-catch-up ceiling annually; workers under 50 are capped at $23,000.
$8,000
2024 maximum IRA contribution, age 50+
The $1,000 IRA catch-up brings the total above the standard $7,000 limit; starting in 2024 this amount is indexed to inflation.
$10,000+
SECURE 2.0 catch-up limit, ages 60 to 63
Beginning in 2025, workers aged 60 to 63 in employer plans can contribute the greater of $10,000 or 150 percent of the standard catch-up amount.
Your 50s often bring financial conditions that make these contributions more reachable. Mortgage balances may be lower, children may be financially independent, and earnings often peak in this decade. The decade before retirement explains how those converging factors can free up cash to direct toward retirement accounts.
The SECURE 2.0 expansion for ages 60 to 63
The SECURE 2.0 Act, signed into law in 2022, introduced a higher catch-up limit for workers aged 60 to 63 in employer-sponsored plans, effective starting in 2025. This tier allows contributions of the greater of $10,000 or 150 percent of the regular catch-up limit, indexed to inflation. Workers aged 64 and older revert to the standard catch-up amount.
This change recognizes that the four years immediately before many workers reach full Social Security retirement age are particularly valuable for building account balances. If you fall in this age window, confirm the current limit with your plan administrator before setting your contribution elections for the year.
For a fuller picture of why closing the savings gap in these years is harder than the numbers alone suggest, the article why catching up on retirement savings is harder than it looks covers the compounding disadvantages late starters face.
Common obstacles and how to address them
The most frequent barrier is cash flow: many households in their 50s carry competing demands such as college tuition, aging-parent support, and remaining mortgage payments. Before increasing contributions, running a detailed expense audit often reveals discretionary spending that can be redirected. The saving pitfalls that quietly erode retirement progress in mid-life article covers the specific spending patterns most likely to undercut this effort.
A second obstacle is employer-plan confusion. Some workers assume catch-up contributions happen automatically once they turn 50. In most plans, you must actively update your contribution election. Log into your plan portal or contact your HR department to set the higher deferral amount.
Employer matching is another point of confusion. Matching contributions are usually calculated on standard deferrals only, up to a stated percentage of salary. The catch-up portion typically does not trigger additional matching, though plan rules vary. Read your summary plan description to understand exactly how your employer calculates the match.
This article is for informational purposes only and does not constitute personalized financial, tax, or investment advice. Contribution limits, rules, and tax treatment can change. Consult a qualified financial adviser or tax professional before making decisions about your retirement accounts.
Frequently Asked Questions
Saving Strategies Editorial Team
Saving Strategies Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View author profile