
The 50s Savings Surge: Why the Decade Before Retirement Is Your Most Powerful
Explore why your 50s represent a unique financial window, with lower childcare costs and peak earning years converging to accelerate retirement savings.
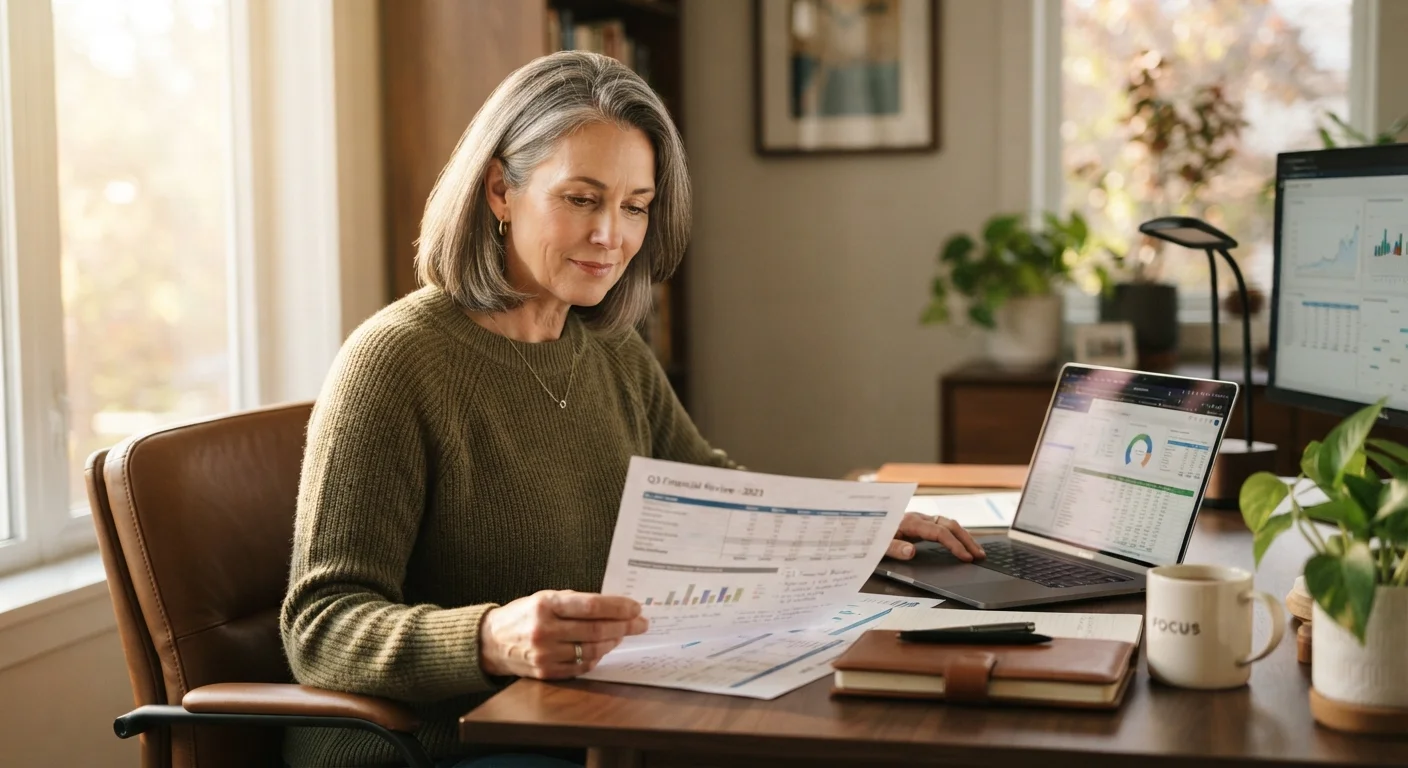
Photo: shapingfinances.com editorial
—— In This Article
Key Takeaways
- Your 50s often bring lower household costs and higher earnings at the same time, creating real savings capacity.
- Catch-up contribution rules let workers over 50 add more to retirement accounts each year.
- Eliminating high-interest debt before retirement protects the income you will rely on later.
- A coverage review in your 50s can prevent insurance gaps from derailing retirement plans.
- Even moderate lifestyle adjustments can redirect thousands of dollars annually toward savings.
What makes your 50s different from earlier decades
In your 30s and 40s, competing financial demands pull in multiple directions: childcare, school costs, building an emergency fund, and often a mortgage in its highest-interest years. By your 50s, many of those costs have fallen or disappeared. Children are more financially independent, the mortgage balance is smaller, and career earnings have often reached their highest point.
This convergence is not guaranteed for everyone, but it is common enough that financial planners treat the pre-retirement decade as a distinct planning phase. The question is not whether the opportunity exists; it is whether you recognize and use it before it passes.
Two forces are working in your favor at the same time: your capacity to save is higher, and the IRS allows you to save more. Workers aged 50 and older can make catch-up contributions to 401(k)s and IRAs, increasing the amount they can shelter from taxes each year.
Where the extra capacity comes from
A household that spent $15,000 to $20,000 annually on dependent children now has that sum available. Add the reduction in term life insurance premiums as coverage needs shrink, and the cash flow shift can be substantial. Many people in their 50s also carry less revolving debt than they did at 35.
Wages for full-time workers typically peak in the late 40s to mid-50s in the United States, according to Federal Reserve data. That means your gross income is likely higher now than it will be at any other point in your career, while your effective tax rate on retirement contributions remains the same or improves if you are maxing out deductible accounts.
$7,500
Annual 401(k) catch-up contribution limit for workers 50+
The IRS sets this amount (as of 2024) as the additional contribution workers aged 50 and older can make to a 401(k) beyond the standard $23,000 limit.
$1,000
Annual IRA catch-up contribution for workers 50+
Workers aged 50 and older can contribute an additional $1,000 per year to a traditional or Roth IRA beyond the standard annual limit, per IRS rules.
55%
Americans who feel behind on retirement savings
A 2023 Federal Reserve Report on the Economic Well-Being of U.S. Households found a majority of non-retired adults expressed concern about having adequate retirement savings.
The combination is straightforward: more income in, fewer mandatory expenses out, and higher contribution ceilings. If you redirect even half of the freed-up cash flow, the impact on your retirement account balance over ten years can be significant. Past investment returns cannot be guaranteed, but the arithmetic of consistent, larger deposits is reliable.
Tactics that work in this window
Maximize tax-advantaged accounts first. Before directing extra cash anywhere else, confirm you are contributing at least enough to your 401(k) to capture any employer match, then work toward the full contribution limit including catch-up amounts. The tax deferral compounds the benefit over the remaining working years.
Audit your spending for structural savings. An expense audit is not about deprivation; it is about finding spending that no longer reflects your priorities. Subscriptions, insurance premiums, and recurring services that made sense five years ago may not now. Moderate lifestyle adjustments can redirect meaningful sums without reducing quality of life.
Address remaining high-interest debt. Carrying credit card balances or personal loans at high interest rates into retirement creates a drag on fixed income. Strategic debt management in your 50s should run alongside, not instead of, increased retirement contributions.
Review your insurance coverage. As circumstances change, some coverage becomes unnecessary and some becomes more important. A systematic coverage review can eliminate wasted premiums and prevent gaps that could force large out-of-pocket expenses in retirement.
What can undermine the surge
The 50s savings window closes quietly if you are not watching for the ways it erodes. Lifestyle creep is the most common threat: when expenses fall, spending often rises to fill the gap instead of flowing into savings. A new car, more frequent travel, and home renovations are all reasonable choices, but each one reduces the savings capacity the decade is meant to provide.
Common saving pitfalls in mid-life also include supporting adult children financially beyond a reasonable point, under-using employer retirement matching, and holding excess cash in low-yield accounts when tax-advantaged vehicles have room.
Income disruption is another real risk. Disability insurance after 50 is worth reviewing, because an unexpected health event in your late 50s can interrupt the contributions you planned to make during these high-earning years.
Understanding how your savings rate compares to investment return as a lever for retirement readiness can help you decide where to focus energy. In many cases, increasing what you contribute has more impact at this stage than chasing higher returns, particularly with a shorter time horizon.
This article is for general informational purposes only and does not constitute personalized financial, tax, or investment advice. Contribution limits and tax rules change periodically; verify current figures with the IRS or a qualified financial adviser. Consult a licensed financial professional before making decisions specific to your situation.
Frequently Asked Questions
Saving Strategies Editorial Team
Saving Strategies Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View author profile