
Why Paying Off Debt and Saving for Retirement Are Not Mutually Exclusive
Many adults in their 40s and 50s assume they must clear all debt before saving. This article explains how to pursue both goals at the same time, with caveats.
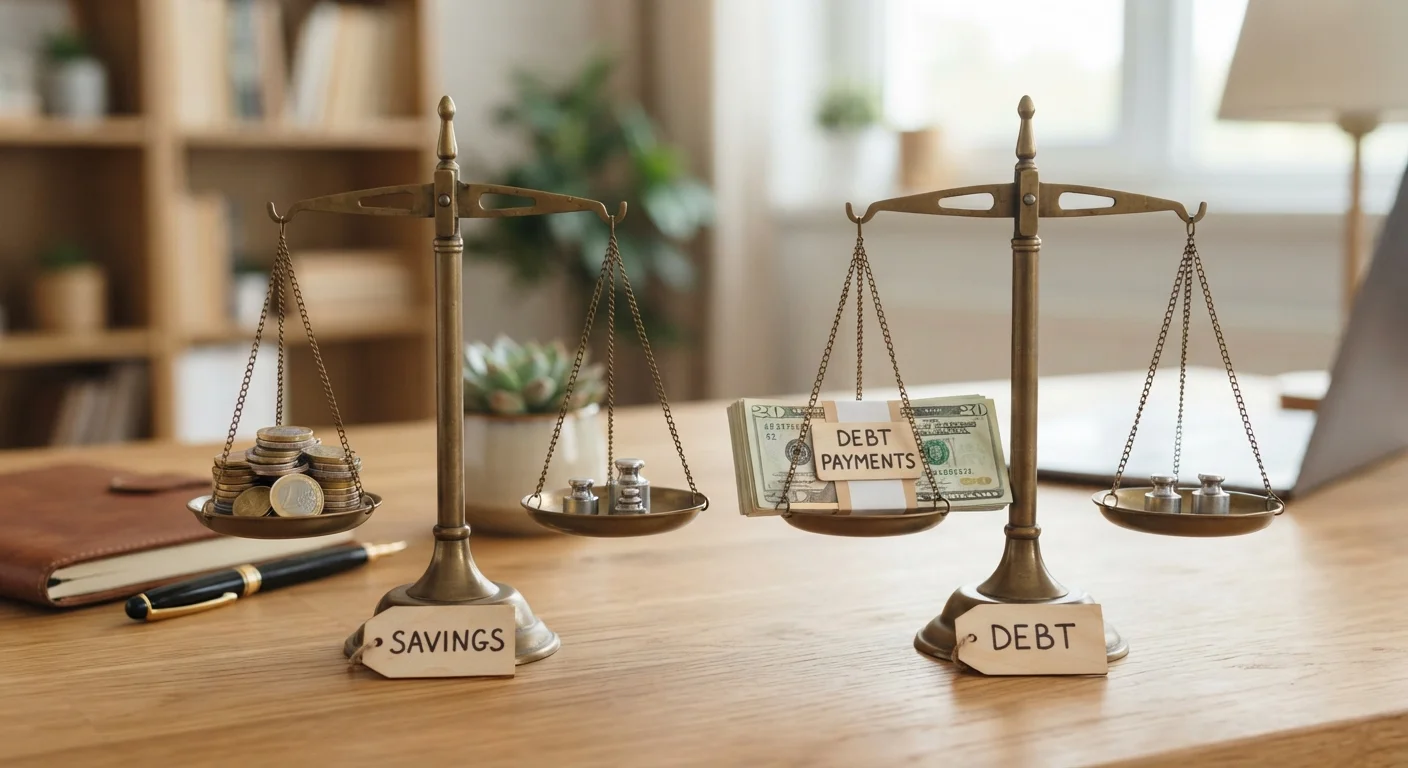
Photo: shapingfinances.com editorial
—— In This Article
Key Takeaways
- Waiting until debt is fully cleared before saving can cost years of compound growth.
- Employer 401(k) matches are free money that debt payoff alone cannot replace.
- High-interest debt deserves aggressive attention, but low-rate debt can coexist with saving.
- Catch-up contribution rules let adults 50 and older invest more each year in tax-advantaged accounts.
- A split strategy, directing some dollars to debt and some to retirement, is workable for most mid-life earners.
The all-or-nothing trap
A common assumption among adults in their 40s and 50s is that debt must be gone before retirement saving can begin in earnest. The logic feels sound: eliminate the liability, then build the asset. In practice, that sequence can cost a decade or more of tax-advantaged growth that no future contribution rate can fully recover.
The tension is real. Debt carries interest charges that drain cash flow, while retirement accounts depend on time and compounding to grow. But these two pressures do not cancel each other out automatically. The right balance depends on interest rates, employer benefits, account types, and how many working years remain. Weighing debt payoff against retirement investing requires looking at both sides of that equation, not just the liability column.
This article corrects the most persistent myths that push mid-life earners toward an all-or-nothing choice they do not have to make.
This article is for general informational purposes only and does not constitute personalized financial, tax, or legal advice. Consult a licensed financial professional before making decisions based on your individual circumstances.
Myths and facts about debt and retirement saving
The following myth-and-fact pairs address the specific misconceptions that most often delay action for adults aged 40 to 60.
Myth
You should pay off all debt before putting money into retirement accounts.
Fact
Carrying certain debts while contributing to retirement accounts can produce a better financial outcome, depending on the interest rates involved and available employer matches.
The cost of debt is its interest rate. The benefit of a retirement contribution is its expected long-term return, plus any tax advantage or employer match. When an employer matches contributions dollar for dollar, that match is an immediate return that almost always exceeds the cost of carrying low-to-moderate interest debt. Skipping the match to pay debt faster means forfeiting money that cannot be recouped later. Managing debt strategically in the years before retirement walks through how to sequence these decisions by debt type and rate.
Myth
Debt payments and retirement contributions compete for the same dollars, so one must stop for the other to grow.
Fact
Both goals draw from discretionary cash flow, but a budget structured around minimum debt payments plus a fixed contribution rate can fund both simultaneously.
Most households carry some fixed expenses and some discretionary ones. The question is not whether there is room for both goals but how much room there is and how to allocate it. A monthly budget that assigns a specific dollar amount to debt reduction above minimums and a separate amount to retirement contributions treats both as non-negotiable line items. Discretionary spending adjusts around them, rather than retirement saving being the first thing cut when debt feels heavy. See debt management strategies for frameworks that support this approach.
Myth
Compound growth only matters when you start in your 20s or 30s. Starting at 50 is too late.
Fact
Compound growth benefits any balance that remains invested over time. A 50-year-old with a 15-year horizon before traditional retirement age still has meaningful time for growth.
A dollar invested at 50 in a tax-advantaged account can still benefit from 15 or more years of growth before a typical retirement date, and often longer if the account is not drawn down immediately at retirement. Catch-up contribution limits exist precisely because lawmakers recognized that mid-life earners can make meaningful progress with aggressive saving in the final working decade or more. The returns are not identical to starting at 25, but the gap between contributing now and waiting until debt is cleared is usually larger than people expect. Past performance does not guarantee future results, and all investments carry risk.
Myth
All debt is equally urgent, so every extra dollar should go to debt before anything else.
Fact
Debt urgency depends on the interest rate. A 3 percent mortgage and a 22 percent credit card balance call for very different responses.
High-interest consumer debt, particularly credit card balances, erodes wealth faster than most investment accounts can grow. Paying those down aggressively before adding contributions beyond an employer match is generally sound. Low-rate debt, such as a fixed-rate mortgage or a federal student loan at 4 to 5 percent, does not carry the same urgency. Directing extra cash toward those balances while pausing retirement contributions is unlikely to improve the overall picture and may delay account growth that compounds over time. Debt myths that affect adults in their 40s and 50s covers additional misconceptions that distort how people rank their obligations.
Myth
Once you have debt, you are not a responsible saver.
Fact
Debt and saving coexist for most American households. Carrying debt does not disqualify someone from building retirement assets.
According to Federal Reserve data, a large share of households approaching retirement age carry some form of debt, including mortgage balances and installment loans. The presence of debt is not itself a sign of financial failure, nor does it mean saving is irresponsible. The responsible choice is to understand the cost of each liability, protect tax-advantaged contributions where the math supports it, and reduce high-rate debt systematically. Framing debt as a moral barrier to saving often results in paralysis rather than progress.
Putting a split strategy into practice
A workable split starts with two numbers: the interest rate on each debt and the match rate your employer offers on retirement contributions. If your employer matches 50 cents on every dollar up to 6 percent of salary, contributing at least that 6 percent captures the full match before directing extra cash toward debt. No debt payoff strategy produces a guaranteed 50 percent return on the next dollar spent.
After capturing any available match, rank remaining debts by interest rate. Consumer debt above roughly 7 to 8 percent typically warrants accelerated payoff before additional retirement contributions beyond the match threshold, because the interest cost is likely to exceed realistic long-term investment returns. Debt below that range, including many mortgage and federal student loan balances, can often be carried alongside steady retirement contributions without a significant net cost.
Adults 50 and older can use IRS catch-up contribution rules to deposit more than the standard annual limit into a 401(k) or IRA. For 2024, the 401(k) catch-up amount is $7,500 above the standard $23,000 limit, and the IRA catch-up is $1,000 above the $7,000 standard limit. These figures are set by the IRS and may change; verify current limits at IRS.gov before contributing. A structured debt payoff plan for adults 10 to 20 years from retirement can help you integrate these contribution windows into a broader financial roadmap.
Tracking both goals on a single monthly budget, rather than separate mental accounts, makes the trade-offs visible and prevents either goal from being neglected when cash flow tightens. Consistent habits that support steady debt reduction apply equally to keeping retirement contributions funded through lean months.
Saving Strategies Editorial Team
Saving Strategies Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View author profile