
Why Minimum Payments Feel Safe But Often Are Not
Paying only the minimum each month can stretch a balance for decades. Here is how the math works and what a more informed repayment approach looks like.
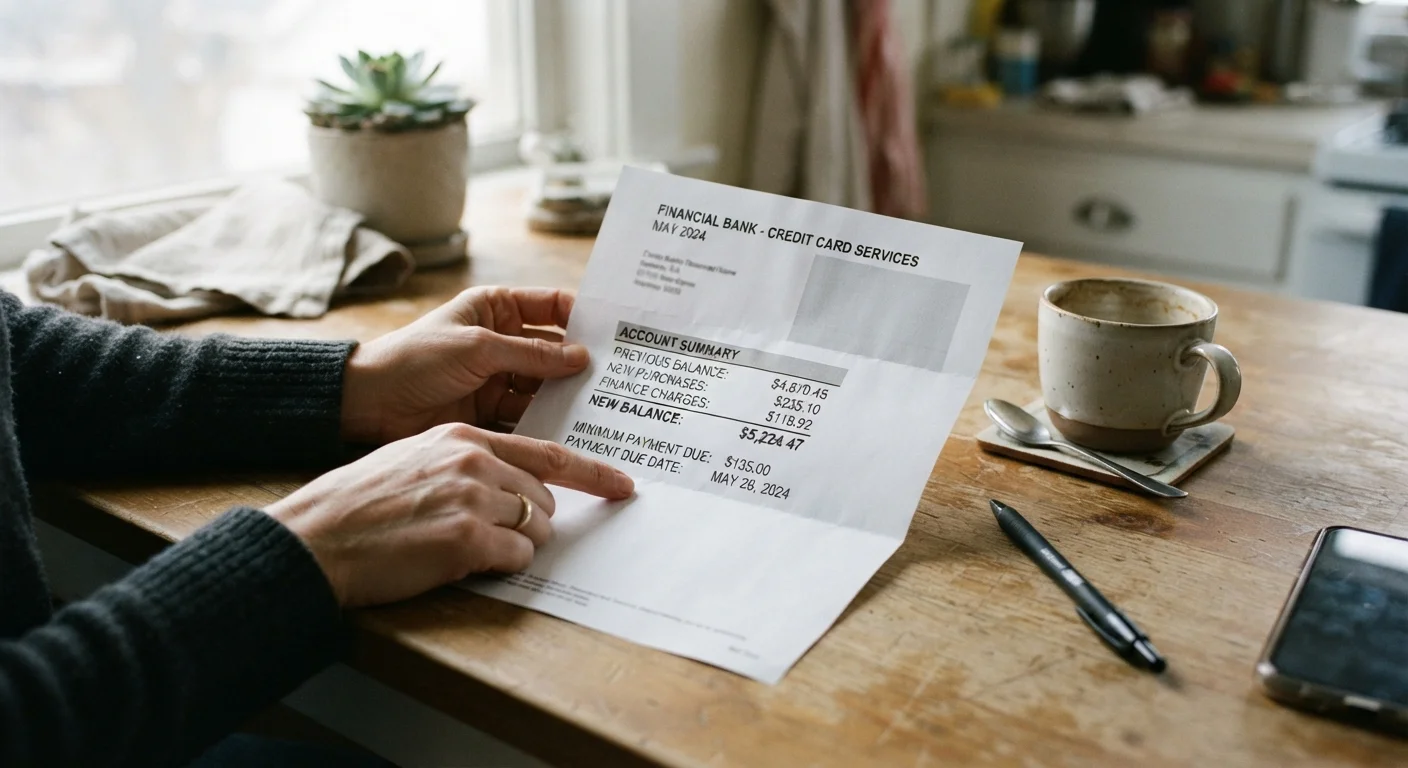
Photo: shapingfinances.com editorial
Key Takeaways
- Minimum payments are designed to keep you in debt longer, not to help you pay it off.
- Interest compounds on the remaining balance each month, often outpacing what you pay.
- Carrying high-interest debt past age 50 directly threatens retirement readiness.
- Paying even modestly above the minimum can cut years and hundreds of dollars from repayment.
- A deliberate repayment strategy protects both your debt timeline and your savings contributions.
How minimum payments keep balances alive
Credit card interest is calculated on the average daily balance, which means even one day of carrying a balance generates a charge. When your payment barely clears the interest that accrued during the billing cycle, the principal barely moves. Issuers set minimum payment formulas, typically 1% to 2% of the balance plus interest, at a level that keeps the account technically current while extending repayment for years.
The Credit Card Accountability Responsibility and Disclosure (CARD) Act of 2009 required issuers to print a minimum payment warning on statements showing how long payoff takes at that rate versus a three-year payoff amount. If you have not read that section of your statement, find it. The contrast is often more than a decade of difference in repayment time.
For adults in their 40s and 50s, that timeline matters in a specific way. A debt that takes 15 years to retire at minimum payments does not disappear before retirement; it travels with you. Debt carried into retirement erodes fixed income and savings in ways that are hard to reverse once Social Security or pension income becomes the primary cash flow.
Treating the minimum payment as the expected monthly payment.
Why it happens: Credit card statements show the minimum payment prominently, and issuers are not required to frame it as a warning. Many cardholders read it as the intended amount, not the floor.
Assuming a zero missed payment record means debt is under control.
Why it happens: Staying current feels like financial responsibility. Because no late fee appears and the credit score holds steady, many people interpret on-time minimum payments as progress.
Prioritizing retirement contributions while carrying 18% to 25% APR balances.
Why it happens: Financial guidance to maximize retirement contributions is sound in most contexts, and people fear missing employer match windows. The math reverses when debt costs exceed likely investment returns.
Consolidating debt without changing the spending pattern that created it.
Why it happens: Debt consolidation lowers the monthly payment, which feels like relief. Without a concurrent spending adjustment, the original accounts often accumulate new balances and total debt rises.
Ignoring the retirement cost of debt carried into your 50s and beyond.
Why it happens: Retirement feels distant when the immediate pressure is a monthly payment. The connection between today's interest charges and a smaller retirement portfolio ten years out is easy to overlook.
A more informed approach to repayment
The debt avalanche method directs any extra payment toward the highest-interest balance first while maintaining minimum payments on all others. This approach minimizes total interest paid and is most effective when two or more balances carry different rates. The debt snowball method, by contrast, targets the smallest balance first regardless of rate; it costs more in interest but can build momentum for people who need early wins to stay consistent.
Either method requires identifying a fixed dollar amount above the minimum that fits your monthly budget. Even $50 to $100 extra per month on a single card can cut years from repayment. A step-by-step debt payoff plan for adults 10 to 20 years from retirement walks through how to structure this alongside ongoing savings contributions.
If cash flow is tight, look at fixed household costs before reducing debt payments further. Practical saving tactics for high-cost households can help surface budget room that is not always obvious. Windfalls such as tax refunds or bonuses also change the payoff math significantly; a lump-sum payment versus continued monthly contributions is worth understanding before you decide where to send that money.
This article is for general informational purposes only and does not constitute personalised financial, tax, or legal advice. Your situation depends on factors specific to you. Consult a qualified financial adviser or credit counselor before making decisions about debt repayment or retirement savings.
Debt Management Editorial Team
Debt Management Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View author profile