
Pension vs. 401(k): Understanding the Core Differences in Retirement Plans
Defined benefit pensions and 401(k) plans work very differently. Here is what each one promises, who bears the investment risk, and how to plan around each.
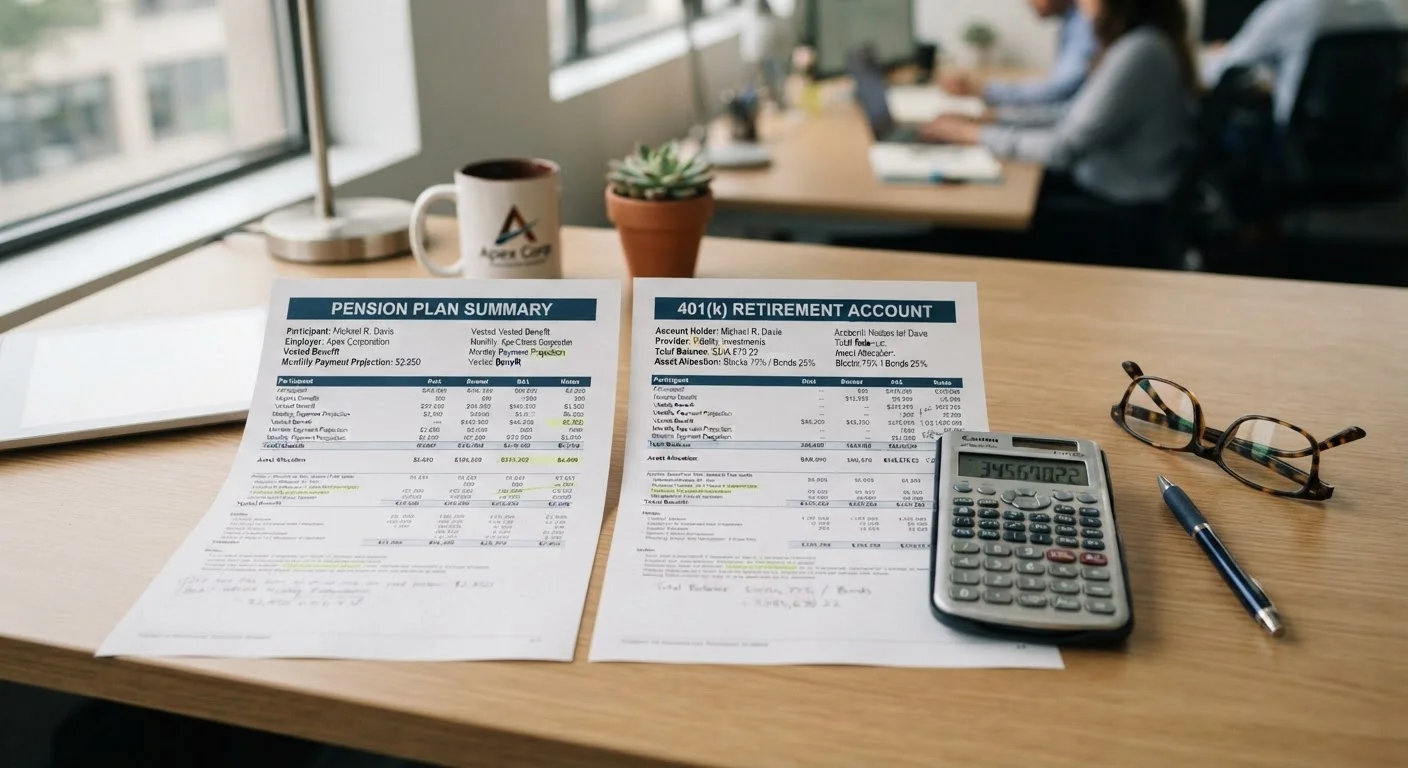
Photo: shapingfinances.com editorial
—— In This Article
Key Takeaways
- A pension pays a fixed monthly amount for life; a 401(k) balance depends on contributions and market performance.
- With a pension, the employer bears the investment risk; with a 401(k), the employee does.
- 401(k) plans are far more common today, as most private employers have shifted away from pensions.
- Both plan types offer tax advantages, but the timing and structure of those advantages differ.
- Having either plan does not eliminate the need to consider Social Security, healthcare costs, and inflation.
- A qualified financial adviser can help you build a retirement income strategy around whichever plan you have.
How each plan is structured
A defined benefit pension promises a specific monthly payment in retirement, calculated using a formula that typically combines your years of service, a multiplier set by the plan, and your average salary near the end of your career. The employer funds the plan, manages the investments, and absorbs any shortfall if returns fall short. You receive the same payment whether markets rise or fall.
A 401(k) works differently at every level. You contribute a portion of each paycheck, often with some employer match, and direct that money into investment options such as mutual funds or target-date funds. The account grows tax-deferred, and the balance you accumulate is exactly what you have to work with in retirement. There is no formula and no guarantee. For a plain-language explanation of how these terms fit into the broader retirement vocabulary, see the retirement planning key terms glossary.
The structural difference matters most when markets are volatile. A pension holder sees no change to their future benefit. A 401(k) holder watches their account balance move with the market, which affects how much they can draw down each year in retirement.
| Criterion | Defined Benefit Pension | 401(k) Plan |
|---|---|---|
| Benefit type | Fixed monthly income for life | Account balance; no guaranteed amount |
| Who bears investment risk | Employer | Employee |
| Employee contribution | Sometimes required; set by plan | Employee-directed; subject to IRS limits |
| Employer contribution | Employer funds the plan | Optional match; varies by employer |
| Portability | Low; benefit stays with employer | High; can roll over to IRA or new plan |
| Investment control | None; employer manages fund | Employee selects from plan menu |
| Vesting period | Typically 5-10 years | Varies; own contributions vest immediately |
| Prevalence today | Mainly public sector | Standard in private sector |
Who bears the investment risk
Risk allocation is the most consequential difference between the two plan types. In a pension, the sponsoring employer, whether a government agency, a school district, or a corporation, takes on the obligation to pay regardless of how the underlying pension fund performs. If the fund is underfunded, the employer must make additional contributions. Some state and local pension funds face real funding pressures, which is a reason pension holders in those systems should monitor their plan's funded status and not treat the benefit as entirely risk-free.
In a 401(k), every dollar of investment risk sits with the employee. A poor sequence of returns in the years just before or after retirement can reduce the account significantly. This is sometimes called sequence-of-returns risk, and it is the primary reason financial planners stress that 401(k) savers need a withdrawal strategy, not just a savings target. To understand how a 401(k) fits alongside other income sources, the article retirement income explained: what it is and where it comes from covers the full picture.
Tax treatment and contribution rules
Traditional 401(k) contributions are pre-tax, meaning they reduce your taxable income in the year you contribute. The money grows tax-deferred, and withdrawals in retirement are taxed as ordinary income. Roth 401(k) contributions, where available, work in reverse: contributions are after-tax, but qualified withdrawals are tax-free. The IRS sets annual contribution limits for 401(k) plans, and workers aged 50 and older can make additional catch-up contributions each year. These limits adjust periodically, so confirming current figures directly with the IRS or your plan administrator is advisable.
Pensions do not have employee contribution limits in the same way, because the benefit is employer-funded. Some pension plans do require employee contributions as a percentage of salary, but the employee generally has no ability to contribute more to increase the benefit. The benefit formula determines the outcome, not how much extra you put in. Both plan types defer taxes on growth, but the mechanics differ enough that comparing them requires understanding your specific plan documents.
Portability and vesting
Vesting schedules determine when you actually own the benefits or contributions an employer has made on your behalf. With a pension, vesting typically requires several years of continuous service, often between five and ten years for full vesting, though this varies by plan. If you leave before vesting, you may forfeit some or all of the accrued benefit.
401(k) employer match contributions are also subject to vesting schedules, but your own contributions are always 100% yours immediately. When you leave an employer, you can roll the vested 401(k) balance into a new employer's plan or into an individual retirement account (IRA), carrying your savings with you. A pension benefit, if vested, is typically frozen at the amount you accrued, and you collect it at retirement age, but you cannot take it with you as a lump sum in most cases.
For workers who expect to change employers, this portability gap is significant. The 401(k) travels with you; the pension does not. For workers who plan to stay with one employer long-term and meet the vesting threshold, the pension's guaranteed income can be a stronger foundation. The article defined benefit vs. defined contribution plans goes deeper on how these structural differences shape long-term income security.
This article is for general informational purposes only and does not constitute personalized financial, tax, or legal advice. Retirement plan rules vary by employer and plan type. Consult a qualified financial adviser or tax professional before making decisions about your own retirement strategy.
Retirement Income Editorial Team
Retirement Income Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View author profile