
Defined Benefit vs Defined Contribution Plans: What the Difference Means for Your Retirement Income
Pension or 401(k)? Learn how defined benefit and defined contribution plans work differently and what each means for your long-term income security.
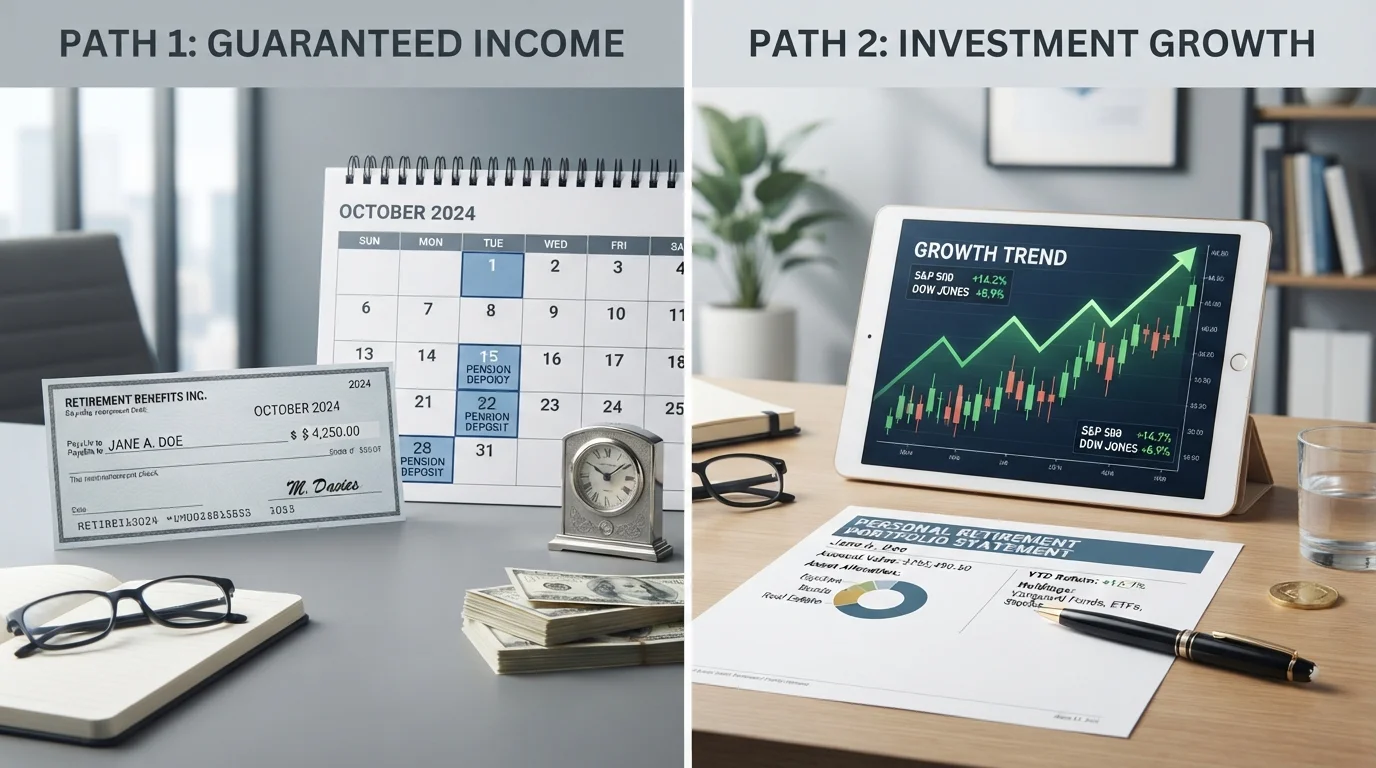
Photo: shapingfinances.com editorial
—— In This Article
Key Takeaways
- Defined benefit plans pay a set monthly income in retirement, funded and managed entirely by the employer.
- Defined contribution plans, like 401(k)s, grow based on contributions and investment returns, with no guaranteed payout.
- Investment risk sits with the employer in a defined benefit plan and with the employee in a defined contribution plan.
- Many private-sector workers now have only defined contribution plans, making personal savings discipline more critical.
- Both plan types have tax advantages, but the timing and structure of those advantages differ meaningfully.
How each plan type works
A defined benefit plan is what most people call a pension. Your employer promises to pay you a specific monthly amount when you retire, calculated using a formula that typically weighs your years of service and your final average salary. The employer funds the plan, manages the investments, and absorbs any shortfall if returns fall short. You receive a check, usually for life, regardless of what the stock market does.
A defined contribution plan works differently. You, your employer, or both contribute a set amount to an individual account in your name. That money is then invested, typically through a menu of mutual funds, and the account grows or shrinks with market performance. When you retire, you draw from whatever balance has accumulated. A 401(k) is the most common version; 403(b) plans serve nonprofit and educational employees, and 457(b) plans serve many government workers. For a fuller picture of how these plans fit into overall retirement income, see Retirement Income Explained: What It Is and Where It Comes From.
| Criterion | Defined Benefit Plan | Defined Contribution Plan |
|---|---|---|
| Who funds the plan | Employer | Employee (often with employer match) |
| Payout structure | Fixed monthly income for life | Account balance; withdrawals vary |
| Investment risk | Employer bears the risk | Employee bears the risk |
| Portability | Limited; may lose benefit if you leave early | High; can roll over to new plan or IRA |
| Employee contribution limit (2024) | Not applicable | $23,000 ($30,500 with catch-up) |
| Required Minimum Distributions | Not required (paid on fixed schedule) | Required from age 73 |
| Availability | Mostly public sector and some unions | Widely available in private sector |
Who bears the investment risk
This distinction matters more than any other. In a defined benefit plan, the employer bears investment risk. If the pension fund's portfolio loses value, the employer must make up the difference to meet its payment obligations. Employees receive the promised amount regardless.
In a defined contribution plan, you bear the investment risk entirely. A market downturn in the years just before or after retirement can reduce your account balance substantially, and there is no employer backstop. This is sometimes called sequence-of-returns risk, meaning that poor returns early in your withdrawal years can deplete a portfolio faster than average return figures suggest. For terminology like this explained in plain language, The Language of Retirement: Key Terms Every Saver Should Understand is a useful reference.
Workers in defined contribution plans can manage this risk through asset allocation, but managing it well requires consistent attention and at least a basic understanding of how diversification works across different market conditions.
Vesting, portability, and contribution limits
Defined benefit plans typically require you to work for an employer for a minimum period before you earn the right to receive a pension. This is called vesting. Leave before you are fully vested and you may forfeit some or all of your benefit. Vesting schedules vary by plan, though federal law sets maximum vesting timelines for private-sector pensions under the Employee Retirement Income Security Act (ERISA).
Defined contribution plans also have vesting schedules for employer contributions, but your own contributions are always yours immediately. Portability is a clear advantage: when you leave a job, you can roll a 401(k) balance directly into an IRA or a new employer's plan without tax consequences if done correctly.
On contributions, the IRS sets annual limits for defined contribution plans. For 2024, the employee contribution limit for a 401(k) is $23,000, with an additional $7,500 catch-up contribution allowed for those aged 50 and older. Defined benefit plans have no employee contribution limit in the same sense because contributions are the employer's responsibility. For a side-by-side look at how pensions and 401(k)s compare on these dimensions, Pension vs. 401(k): Understanding the Core Differences in Retirement Plans goes deeper.
15%
Private-sector workers with pension access
The Bureau of Labor Statistics reported in 2023 that only about 15% of private-sector workers had access to a defined benefit plan, down sharply from prior decades.
$30,500
Max 401(k) contribution for savers aged 50+
The IRS sets the 2024 combined 401(k) limit at $30,500 for workers aged 50 and older, including the $7,500 catch-up contribution.
Age 73
Age when RMDs begin for defined contribution plans
Under the SECURE 2.0 Act, the Required Minimum Distribution starting age increased to 73 for most defined contribution plan holders.
Tax treatment and income in retirement
Both plan types use pre-tax dollars in their basic structure, which means contributions reduce your taxable income in the year they are made. Defined benefit pension payments are taxed as ordinary income when received. Defined contribution plan withdrawals are also taxed as ordinary income for traditional accounts, though Roth 401(k) contributions, made with after-tax dollars, can produce tax-free withdrawals in retirement if IRS rules are met.
Defined contribution plans are also subject to Required Minimum Distributions (RMDs), beginning at age 73 under current IRS rules. RMDs require you to withdraw a minimum amount each year based on your account balance and life expectancy tables, whether you need the money or not. Traditional pension payments do not have an RMD requirement because they are already paid out on a fixed schedule.
If you have only a defined contribution plan and want to replicate the income predictability of a pension, one option some retirees consider is purchasing an annuity with part of their savings. This is a decision that warrants careful analysis and consultation with a licensed financial professional, as annuity terms vary widely and some carry significant costs. Retirement Insurance Explained: What It Is and Why It Matters After 60 covers how insurance products can intersect with retirement income planning.
This article is for general informational purposes only and does not constitute personalized financial, tax, or investment advice. Retirement plan rules, contribution limits, and tax treatment can change. Consult a qualified financial adviser, tax professional, or benefits specialist for guidance specific to your situation.
Retirement Planning Editorial Team
Retirement Planning Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View author profile